

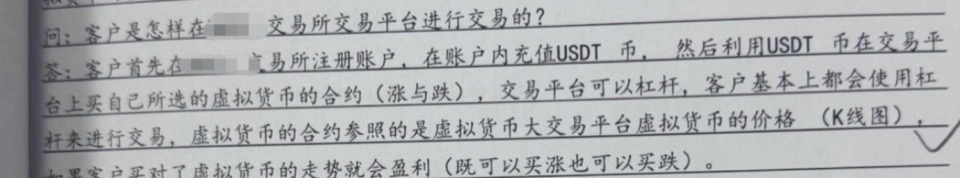
In the crypto asset exchange cases handled by our team's lawyers, investigators often describe perpetual contracts in their interview records as a gambling game of guessing whether prices will rise or fall, in order to characterize exchange personnel as committing the crime of running a casino. As a result, subsequent case handlers, reading only the contents of the records, also mistakenly believe that perpetual contracts are a form of gambling similar to guessing big or small.
In discussions with peers about whether perpetual contracts count as gambling, the conversation always ends up in the argument of "are perpetual contracts futures? If so, why is there no physical delivery? Perpetual contracts with leverage will besubject to forced liquidation." Even if I can establish that perpetual contracts are a new form of futures, and draw an analogy to index futures, which also have no physical delivery, it still seems difficult to persuade the other side.
Later I came to understand that the essence of these discussions is not whether perpetual contracts are futures, but that we should have a clear marker to distinguish financial activities from gambling activities.
Sowhat is the marker that distinguishes financial activities from gambling activitiesWhat does it consist of?
First, is it whether something is lawful or unlawful? Obviously not; illegal financial activities are still financial activities, and some gambling activities are lawful (Macau casinos).
Second, is it whether leverage is used? Obviously not; leverage is entirely normal in futures markets, and a great deal of gambling activity involves no leverage (WeChat red-envelope grabbing, mahjong).
Third, is it the randomness of the outcome? This seems somewhat closer. Why are we accustomed to saying trading stocks, trading futures, and trading contracts, yet also accustomed to saying betting on football and betting on horse racing? It seems that the outcomes of football matches and horse races are uncontrollable, whereas stocks, futures, and contracts all have candlestick charts to look at.
In Guiding Case No. 146Casino establishment caseIn this case, Chen Qinghao and others were a typical example of using the concept of financial activity to conduct gambling activities.
In this case, the perpetrators used foreign exchange trends to operate a casino: they downloaded and installed market quotation receiving software and a self-made plug-in for the Longhui website, selected a certain foreign exchange trading product, chose an expiry time ranging from one minute to one hour, entered the transaction amount, and clicked the "buy up" or "buy down" button to complete the transaction. If the direction of the rise or fall was correctly predicted, they could profit; if the direction was wrongly predicted, the entire principal was lost. Is this kind of futures board not a typical binary guess-the-size gambling board? They also have candlestick charts, but they used the upward and downward ranges of the candlestick charts to play a gambling game, and there is no problem at all in determining this to be casino establishment. Therefore, randomness of results should not be the marker distinguishing gambling games from financial activities.
Then it is obvious thatthe distinction between financial activities and gambling activities lies in whether the right to choose risk control is in the hands of the participants.
Participants in gambling activities are completely unable to control risk, commonly known as buying and letting go. In financial activities, however, the right to control risk is in one's own hands, just as when you think a stock has fallen, you can promptly sell to stop losses, unlike Guiding Case No. 146, which usedforeign exchange futuresfinancial concepts to engage in gambling, where one cannot leave before the result is announced. If a stock rises, and you do not sell and exit, you also cannot say that you have made a profit. The same is true of perpetual contracts: if you go long but the coin price falls, you can choose to close the position to stop losses, or you can hold until the coin price rises and then close the position, and you will ultimately still make a profit.
Negative argument that perpetual contracts are gambling
Based on the above considerations, we can easily look back at the domesticweb3ecosystem discussion provoked by the view of the Pingjiang County People's Court thatcoin customersExchangeThe logic for treating perpetual contracts on exchanges as gambling is as follows:
1. Virtual currency trading is illegal.
—Obviously, illegality does not equal gambling; it is unclear why this is raised. Mainland China is not Macau—is there any legal gambling there?
2. The rise and fall of virtual currencies is characterized by irregularity, randomness and contingency.
—The trading pairs BTC and ETH offered under perpetual contracts on Coin Guest Exchange clearly both exhibit regular, traceable price fluctuations in their candlestick charts that correlate with the Nasdaq and U.S. equity market movements.
3. Compared with formal futures, the obvious differences are: no physical delivery, no agreed delivery time, and perpetual contract trading hours of 7x24.
—Obviously, lawyers only understand law and have limited understanding of the securities world. Perpetual contracts are a new form of development of formal futures; when stock index futures appeared in February 1982, futures without physical delivery had already been achieved; by 1993, some had proposed perpetual contracts without a set delivery time; and in 2015, through the widespread establishment of virtual currency exchanges, perpetual contracts found their best application scenario—crypto assets.
4. Platforms amplify speculative risk through high leverage, which is high-risk; once high leverage is used, it is very easy to cause a "liquidation."
—Leverage is not a characteristic of gambling; too many financial activities involve leverage, and too many gambling activities involve no leverage. This case holds that high leverage will "very easily" cause liquidation, but does not discuss the relationship between margin and leverage—closing a position can be achieved through margin, or even by adding margin to offset leverage, so as to prevent liquidation from occurring, which is clearly different from gambling where, after a bet is placed, only the dealer determines the outcome. Participants in contracts can control the occurrence of results; this kind of speculative trading with a high degree of dominance is fundamentally different from gambling transactions in which the bet is final once placed.
The essential difference between perpetual contracts and gambling
Accordingly, this article also wishes to treat the perpetual contracts of a licensed exchange in a foreign jurisdiction such as Binance as a standard model—users can participate in contract trading of virtual currencies such as BTC and ETH by going long or short. The platform adopts a market maker model, throughAPI interfaceLiquidity support is provided by a professional team and combined with a high-frequency trading system to achieve rapid order matching. To ensure a dynamic balance between contract prices and spot prices, Binance introduced the funding rate mechanism, which uses periodic fee adjustments to incentivize both long and short parties to balance their positions. This design is highly similar to the mechanisms of futures trading in traditional financial markets (such as the Chicago Mercantile Exchange).
As a basis for discussion (excluding those fraudulent schemes and gambling schemes that operate under the name of perpetual contracts but in reality involve exchanges entering the market to bet against players), let us set out in detailthe differences between perpetual contracts and gambling: Perpetual contracts do not have "stake placed, hands off" or a fixed gambling settlement time. In betting on football, horse racing, or guessing big or small, once a bet is placed it cannot be withdrawn midway; the core feature of gambling is thus "stake placed, hands off." This contains two meanings: first, there is an exact betting time point; before the betting cut-off time, the bet may be changed, and after it may not. Second, after the stake is placed and hands are off, there will be another exact and fixed time point at which the outcome of the wager is revealed and settled, with the losing party paying the winning party. After betting, no change is possible until the fixed time point reveals the result. For example, as in Guiding Case No. 146 mentioned above.
1. Perpetual contracts have no "stake placed, hands off" mechanism
Traders of perpetual contracts may close positions at any time to stop loss or take profit, and may add virtual assets to lower (raise) their positions; there is no mandatory betting cut-off time.
This design allows participants to adjust strategies according to market dynamics. Taking recent Ethereum market conditions as an example, after an Ethereum contract trader opens a long position, if the price moves adversely, the trader may immediately close the position to avoid further losses; the trader may also hold the position and wait for a rebound, turning an originally losing position into a profit, and may even add to the position at a low price so as to achieve a profit even when the Ethereum price is below the price at which the position was first opened.
It can be seen that the feature of perpetual contracts that "trades may be made at any time (including supplementary trades) and settlement of trades may be requested at any time" clearly negates the characterization of perpetual contracts as a game of guessing big or small, and has the characteristic of being contrary to "stake placed, hands off"; it is truly difficult to equate them with gambling games.
2. Perpetual contracts can technically avoid the occurrence of "forced liquidation"
All casinos inevitably hope that every wager will produce a result as quickly as possible so that the house can settle as soon as possible; therefore, gambling must have a clear result to calculate wins and losses, and without a result it cannot proceed.
However, perpetual contracts technically permit "never settling"; from the outset, perpetual contracts have no expiry date, and users may hold them indefinitely. Among other things, in the case of buying to go long, users may also trade with one-time leverage, which produces the effect of holding Bitcoin or Ethereum spot; considering that over the long term the funding rates for holding contracts are generally balanced between long and short, in theory under such circumstances the user can never be liquidated.
If leverage is added, then injecting additional funds to eliminate the leverage (or to reach a liquidation price that is almost impossible to hit) can also effectively prevent liquidation. From a casino's perspective, no casino would design a betting game whose settlement outcome can never be awaited, so how can a perpetual settlement contract that can never be liquidated be characterized as gambling?
Outlook
In my previous articles, "Is Cryptocurrency Perpetual Contract Trading Gambling or a Financial Derivative? Mankun Lawyers' Horizontal Comparison of Global Regulatory Status》《"Perpetual Contracts" Should Not Constitute the Crime of Operating a Casino; After Layer-by-Layer Reporting to the Supreme People's Court, They May Be Found to Constitute the Crime of Illegal Business Operations" and in my defense work, I have shown that under global regulatory policies, perpetual contracts are managed from the perspective of financial derivatives. In communications with practitioners at exchanges (licensed or imitating the Binance model), most hold a do-no-evil mindset and have never intended to operate a casino. Of course, during communications with many people, some have jokingly said that contracts are just gambling, but this kind of gambling is more a vague expression of their own speculative mentality, akin to the joke that "trading stocks is gambling."
It is precisely through these rounds of communication that I was prompted to examine in depth where exactly the difference lies between the financial activity of contracts and gambling activity, ultimately arriving at the conclusion of this article. If necessary, I will subsequently update the development history of perpetual contracts—how they evolved from futures contracts to perpetual futures contracts—and explore the significance of perpetual contracts as a financial innovation.
