
“I initially put in RMB 100,000, and after all these years of trading, my account is down to RMB 80,000. How can I still receive a tax self-review reminder?Does that mean I have to pay additional tax even though I lost money?”
This is the biggest source of confusion for many veteran traders who have been through bull and bear markets.
During the bull market back then, the assets at one point grew to several hundred thousand yuan. In between, there were countless token swaps, staking, losses, and even forced liquidations, and in the end the overall account was still down RMB 20,000. When most people receive a self-review reminder from the tax authorities, their first reaction is: take the ending balance and subtract the initial investment, and the result is a net loss of RMB 20,000—how could there possibly be taxable income?
Unfortunately, however, “the ultimate profit or loss on a person’s total assets” and “statutory taxable income realized on an annual basis” are two entirely different concepts under tax law.
To work out whether additional tax is owed and how much, you must reconnect every trade, token swap, loss and change in status over these years. Of course, the reverse is also true—the tax authorities will not simply add up all your incoming transaction records and force you to pay tax on that basis.
In recent years, the tax authorities have continued to strengthen their scrutiny of the reporting of overseas income. Holders of crypto assets who are involved with overseas trading platforms and cross-border fund flows should also re-examine their historical transaction records and check whether there is any income that needs to be reported in accordance with the law.
I. If I clearly lost money in the end, why is the money I made earlier still being counted?
Here is a simple example (all of the following are hypothetical scenarios, used only to illustrate the calculation logic; China currently has no unified tax calculation rules for crypto asset transactions):
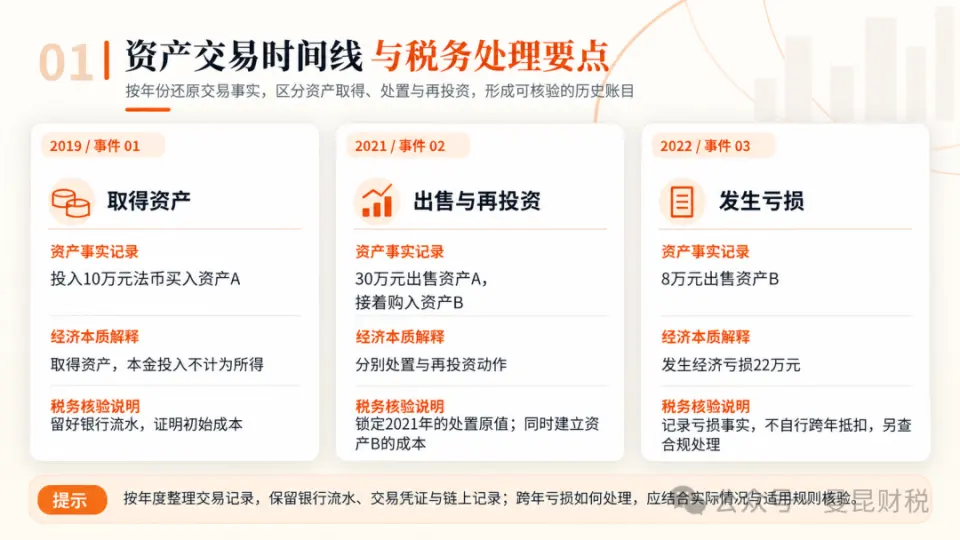
● 2019: You put in RMB 100,000 to buy crypto asset A.
● 2021: The bull market arrived, asset A rose to RMB 300,000, you chose to sell, and you made a profit of RMB 200,000. You then put all of that RMB 300,000 into asset B.
● 2022: The bear market arrived, asset B kept falling, and in the end you sold it for only RMB 80,000, a loss of RMB 220,000.
After several years of ups and downs, only 80,000 yuan remained of the initial 100,000 yuan investment, leaving an overall loss of 20,000 yuan.
Reading this, you may wonder: since no money was ultimately made, why should tax payment even be considered?
The issue is that whether you ultimately made a profit and whether a particular past transaction generated taxable income are not entirely the same question.
Consider the example above. In 2021, you sold Asset A for 300,000 yuan, and that transaction generated a gain of 200,000 yuan. Assume that, upon specific tax analysis, the transaction is treated as "income from transfer of property" under the law, and the purchase cost of 100,000 yuan can be proven; disregarding other deductible factors for the time being, at a tax rate of 20%, the illustrative tax amount would be:
(300,000 yuan − 100,000 yuan) × 20% = 40,000 yuan.
But in 2022, your investment in Asset B suffered a loss of 220,000 yuan. Although this loss genuinely occurred, it does not mean it can be directly used to offset tax that may have arisen in 2021.
The reason is not complicated: for tax purposes, each specific transaction and the applicable rules must be assessed separately; one cannot look only at whether there was an ultimate profit or loss over several years. For transactions treated as income from transfer of property, it is generally necessary to account separately for the transfer revenue, the original cost and reasonable expenses.A gain realized in the previous year cannot simply be wiped out automatically merely because a loss occurred in the following year.
Of course, the 40,000 yuan above is only a hypothetical calculation used to illustrate the issue, and it does not mean that all crypto asset transactions are uniformly subject to individual income tax at 20%. Whether tax is actually payable, which rules apply, and whether the relevant losses can be deducted all need to be determined in light of the specific transaction circumstances and current legal provisions.
Therefore, if you have been through multiple bull and bear markets and want to figure out whether your historical transactions have any tax issues, the first step is not to subtract your original principal from your current account balance, but to separately organize each past purchase, sale, token swap and loss, and then determine which of those transactions may involve a tax obligation.
Only after the accounts are clearly worked out can you further determine how the tax should be calculated and whether supplementary payment is required.
II. How should complex transaction records be sorted out? The first table restores only the "asset facts."
When dealing with high-frequency, cross-chain, multi-platform small transactions, the first step is absolutely not to calculate tax directly, but to establish a purely asset-change table.
Take stock of all your exchange accounts, hardware wallets, and on-chain addresses. List them transaction by transaction by coin type:
● How many coins there were at the beginning of the period
● Increases: deposits, salary, purchases, airdrops, staking rewards
● Decreases: sales, withdrawals, transfers, protocol consumption
● Verify the ending quantity
Key professional operational points:
List coin value fluctuations separately:Rises and falls in coin prices are unrealized gains and losses; as long as you have not sold or exchanged, and the number of coins has not changed, it is not a taxable event.
Internal transfers are not counted twice:Withdrawing from Binance to a MetaMask wallet is an internal transfer and must not be counted twice. However, if a cross-chain bridge or wrapped token (for example, ETH exchanged for wETH) is involved in between, attention must be paid to whether the rights to the asset have undergone a substantive change.
What if the accounts do not reconcile? When you encounter a discrepancy where the accounts do not reconcile, never casually enter an "other income" line to force the figures to balance! The discrepancy may be because you forgot to record a fee, the rebase mechanism, or an in-exchange conversion. If you rashly fill an unclear discrepancy in as "income," you are effectively establishing a potential tax basis against yourself.
Illustrative asset fact organization table (for logical illustration only):
III. Reconstructing the crypto asset evidence chain using the "three-layer working paper method"
Given the high complexity of crypto asset transactions (including missing historical CEX data, dense on-chain DEX interactions, cross-chain bridges and DeFi combinations, etc.), a simple table cannot satisfy verification requirements. In practice, when organizing complex transactions, we rely on the "three-layer working paper reconstruction method" to build a compliance working paper for asset holders that can withstand retrospective review:
Layer one: What happened
First record the facts that can be verified:
● On which day and how much funds were paid to the platform;
● What assets were bought or sold, and in what quantity and at what price;
● To which account or address the assets were transferred in or out;
● What the platform's trade, deposit, withdrawal and fee records are respectively.
Materials that may be used include bank statements, orders exported from the platform, exchange account records, on-chain transaction hashes and contract interaction records.
Different materials can prove different things:Bank statements can prove that funds were paid, but they may not by themselves prove which batch of assets was purchased; an on-chain hash can prove that the corresponding transaction occurred, but it may not by itself prove how much RMB was originally paid.
Second layer: Why did these assets come in, and why did they go out?
The same incoming payment may reflect a completely different economic relationship.
For example, where a developer receives USDT for work, it is first necessary to understand that person's relationship with the payer; for transfers between personal accounts, it is necessary to verify whether the assets have always belonged to the same person; and where a client payment is received, it is also necessary to distinguish personal income from amounts collected on behalf of a company.
Freezes, theft and losses on sale should also be recorded separately. A platform's temporary suspension of withdrawals does not necessarily prove that all assets in the account are irrecoverable; further assessment should be made in light of the platform's announcements, creditor claims, liquidation and actual distributions.
Third layer: How should the tax issues be explained?
Once the facts and the transaction relationships are relatively clear, examine each item in turn:
● which category of income the amount may fall under;
● in which year the acquisition or disposal occurred;
● what evidence supports the original cost and reasonable expenses;
● whether a filing has already been made and whether there is any double counting; and
● which facts and supporting documents remain unverified.
For each amount that needs to be explained, it should be matched, as far as possible, to contracts, orders, platform records, bank statements, or on-chain records.Whichever link cannot be verified, set out the issues to be verified, and do not fill it in with speculation to turn it into a definite figure.
For example, if a person receives token development remuneration and sells the tokens a year later, it may be necessary to examine separately the receipt of the remuneration and the subsequent disposal, and to pay attention to the value linkage between the two, so as to avoid looking only at the final cash-out and also avoid repeatedly counting the same economic amount without distinction.
IV. Historical cost and status determination: uniform assumptions cannot be applied across the board
When organizing crypto asset transaction records spanning many past years, in addition to ascertaining how much was earned and how much was lost each year, two issues cannot be overlooked: what tax status applied in that year? And can the cost of the acquired assets still be proven?
If tax status has changed, the tax rules may also differ
If in recent years you have lived or worked abroad for an extended period, or travelled back and forth between different countries and regions, it is necessary to re-examine your tax resident status for each year.
This is because residence circumstances in different years may affect the scope of individual income tax liability. Determining whether one is a Chinese tax resident requires consideration of factors such as whether one has a domicile within China and the number of days of residence in the relevant year, rather than simply looking at which passport one holds or whether one has an overseas visa.
At the same time, tax resident status and the source of income are two distinct issues. Even if an overseas exchange is used, it cannot be directly concluded that the relevant income is overseas-sourced income.
Therefore, the status in a particular year cannot be directly applied to all past years. Where cross-border residence or income is involved, it is also necessary to make a separate determination based on the specific circumstances and the applicable tax treaties.
For coins purchased many years ago, how can the cost be proven?
Another common issue is that the coins are still there, or were sold long ago, but the original purchase records can no longer be found.
For example, you may be able to find bank statements showing transfers to an exchange several years ago, but that does not necessarily prove how much of which asset that money specifically purchased; although on-chain transaction records can prove that assets moved from one wallet to another, they generally cannot on their own prove how much was paid to purchase them at the time.
In such cases, it is necessary to combine bank statements, exchange orders, deposit and withdrawal records, on-chain transaction records and other materials to reconstruct, as far as possible, the purchase price, transaction quantity and asset flow at the time.
If the same type of crypto asset was purchased in multiple transactions and then sold in batches, the cost calculation becomes even more complex.
Some foreign tax software defaults to the first-in, first-out (FIFO) method or the average cost method to calculate gains, but these methods cannot be directly equated with a unified calculation rule recognized by the Chinese tax authorities. In a specific tax examination, it is necessary to explain, in light of the transaction circumstances, the evidence available and the applicable provisions, how the cost is determined and what the calculation method is based on.
Ultimately, the key to examining historical cost is not to arbitrarily choose an algorithm to make the accounts balance, but to ensure that every purchase, sale and cost is supported by verifiable records.
V. On the limitation period for recovery: does it mean that after 3 years there is no need to worry about it?
Many people have heard that "the tax recovery period is generally 3 years, and 5 years in special circumstances," and therefore assume that accounts from before 2020 no longer need to be reviewed. This understanding is very dangerous!
In what circumstances does the 3-year/5-year limit apply? If at the time you did not intentionally evade or resist tax, but simply did not understand the rules and failed to file a return, the recovery period is indeed generally 3 years (5 years in special circumstances). However, this must be determined on the basis of specific documents and facts, and cannot be applied directly on the mere statement "I did not file a return that year."
There is no time limit for tax evasion/tax avoidance:If it is determined that there was intentional concealment, provision of false materials, or similar conduct, the tax authorities' recovery of the tax owed is not subject to any time limit.
Records from earlier years remain your current "life-saving evidence":Even if the 2019 tax has already passed the limitation period for recovery, you still need your 2019 purchase records! Because if you need to prove in 2021 that your cost was RMB 100,000, you must produce the 2019 purchase vouchers. Erasing old accounts often harms you the most.
VI. Voluntary correction is not equivalent to voluntary surrender, and even less to "penalty exemption"
Hearing that some people go for self-inspection and supplementary tax payment, many people's first reaction is "will I go to prison" or "once I pay, will everything be completely resolved"?
Supplementary tax payment merely corrects the tax records:Voluntary supplementary tax payment is an administrative compliance action; it does not in itself mean you have committed a crime, nor can it be directly equated with "voluntary surrender" under criminal law.
"First-time supplementary payment exempts criminal liability" is conditional:According to the judicial interpretation, if tax evasion, before the public security authority files a case, is fully remedied by paying the tax, late payment surcharges and fines in full within the prescribed period in accordance with the notice issued by the tax authority, criminal liability may indeed not be pursued (provided that no criminal penalty or two or more administrative penalties for tax evasion have been received within five years).
Late payment surcharges and fines are two different things:Tax is the principal, late payment surcharges are charged on a daily basis (the annualized rate is not low), and fines are penalties. In the table, they must be listed clearly in separate columns; do not mix them all together as a "tax rate".
(Note: The State Taxation Administration has published unified Tax Administrative Penalty Discretionary Benchmarks, which will officially take effect on November 1, 2026. Matters handled before that date still need to be determined in light of the specific documents and the principles for applying the old and new rules.)
VII. Correction timeline and closed-loop cross-checking
When organizing the supplementary correction arrangements, it is advisable to record the statutory filing milestones and the actual supplementary correction path separately:
For example, if you have overseas income for the 2025 tax year, the statutory filing deadline is generally June 30, 2026. That window has now passed. If you discover that you previously failed to report, you should not delay until 2027; rather, you should promptly organize the materials and proactively review the remedial path.
VIII. Conclusion
Crypto asset transactions often span multiple platforms, wallets and tax years, and after several market cycles, historical records inevitably become complex. Complex records, however, do not mean they cannot be clarified. By organizing transaction records, reconstructing asset flows, verifying historical costs, and analyzing each item in light of the actual circumstances of each year and the applicable legal provisions, it remains possible to gradually clarify past transactions and potential tax risks.
The purpose of reviewing historical transactions is not simply to calculate a tax amount to be paid retroactively, but to reconstruct the true facts of the transactions and clarify the nature of each item of income, cost and loss. Matters that should be reported and handled in accordance with the law should be handled promptly and in compliance; matters that should not be double-counted or incorrectly characterized must also be explained with sufficient evidence and grounds. Only by getting the accounts clear and explaining the facts clearly can historical tax issues be addressed more reliably.
Appendix: Principal References and Public Information
1. Developments regarding self-review reminders for overseas income: the website of the State Taxation Administration republished a Xinhua News Agency report, "Tax Authorities Remind Taxpayers to Self-Review Overseas Income for 2022 to 2024" (January 2026)
2. Tax basis and filing time: Articles 6 and 13 of the Individual Income Tax Law of the People's Republic of China
3. Rules on foreign tax credits for overseas income: Announcement No. 3 of 2020 of the Ministry of Finance and the State Taxation Administration, "Announcement on Issues Concerning the Administration of the Collection of Individual Income Tax on Overseas Income"
4. Provisions on the limitation period for recovery: Official Reply of the State Taxation Administration on Issues Concerning the Limitation Period for Recovery of Unreported Tax (Guoshuihan [2009] No. 326)
5. Conditions for not pursuing criminal liability for tax evasion: Article 3 of the Interpretation of the Supreme People's Court and the Supreme People's Procuratorate on Several Issues Concerning the Application of Law in the Handling of Criminal Cases Endangering Tax Collection and Administration (Fashi [2024] No. 4)
6. Discretionary benchmarks for tax penalties: Announcement of the State Taxation Administration on Issuing the Discretionary Benchmarks for Tax Administrative Penalties (State Taxation Administration Announcement No. 20 of 2026, effective November 1, 2026)
