
The same on-chain transfer may be a transfer of funds between company wallets, receipt of payment on someone else's behalf, or a client's payment for project fees. The key to determining its nature is not the address, but who owns the assets, why the transfer was made, whether the assets need to be returned, and whether any new economic benefit has been obtained.
Q: If funds are frequently transferred among company wallets, founder wallets and employee wallets, must every transfer be treated as income?
A: The answer may be: the transfer of company assets between different wallets does not generate new income.
It may also be: an overseas client has paid consulting fees into the founder's personal wallet, which has already constituted an item of income whose nature needs to be determined.
On-chain, all such actions are called "transfers", but their legal, accounting and tax consequences may be completely different.
Four things should be examined first: who originally owned the assets, why the transfer was made, whether the assets need to be returned, and whether the recipient has obtained any new economic benefit.
China currently has no nationwide special rules that directly govern the tax treatment of transfers of modern crypto assets between one's own wallets. The following analysis is based on general principles of tax law and presupposes that wallet ownership and the reason for the transfer can be proven.
I. The four most common types of wallet transfers encountered in business operations
The on-chain actions are similar, but the entities behind them and their business purposes differ.
Scenario 1: Transfer from the company treasury to the company operating wallet
A Web3 project transfers 100,000 USDT from the company treasury wallet to an operating wallet for subsequent payment of development, marketing and daily expenses. Both wallets are managed by the company, and the assets remain owned by the company.
Preliminary assessment: If the assets remain owned by the same company before and after the transfer, this is closer to an intra-company reallocation of assets than to a natural person obtaining income.
What most needs to be proven: that the wallet belongs to the company, that the purpose of the reallocation is clear, and that the approval and accounting records correspond.
Greatest risk: where only the founder holds the private keys, yet there is no company wallet inventory, internal resolution or accounting record, it is very difficult for outsiders to determine whether this is a company reallocation or whether the assets have already been transferred to an individual.
Scenario 2: Company assets transferred into a wallet controlled by the foundermulti-signature wallet
For security management purposes, the project company transfers assets into a multi-signature wallet in whose control the founder participates. Technically, the founder holds signing authority; however, this does not mean the assets belong to the founder personally.
Preliminary assessment: the key issue is not who can sign, but whether the wallet holds the assets on behalf of the company and whether the founder is merely performing management duties.
What most needs to be proven: company resolutions, wallet management policies, multi-signature authority arrangements, accounting records, use of funds, and return or handover mechanisms.
Greatest risk: Company assets and the founder's personal assets are commingled in the same wallet, with no separate accounting over a long period, which may later be challenged as compensation, profit distribution, a loan, custody, or another transaction.
Scenario 3: The project party temporarily uses an employee's wallet to receive assets
Due to operational or permission arrangements, an overseas project party temporarily transferred 100,000 USDT into an employee's personal wallet, and the employee subsequently transferred it to an address designated by the company as instructed.
Preliminary assessment: If the employee was under a clear obligation to return or hand over the assets and did not acquire or dispose of them, it is inappropriate to characterize the funds as the employee's income merely because they arrived in the employee's wallet.
What most needs to be proven: Who gave the instruction, why the employee's wallet was used, how long the employee had control, whether the amount transferred out was consistent, and whether the employee obtained fees or other benefits.
Greatest risk: This arrangement itself involves non-standard governance. Frequent use of employee wallets, split transfers out, or routing through the employee's bank account at the same time may expand the risk from tax to financial regulation, anti-money laundering, bank card freezes, and criminal liability.
Scenario 4: An overseas client pays consulting fees into the founder's personal wallet
The founder provides consulting or development services to an overseas client, and the client pays 100,000 USDT into the founder's personal wallet. The founder may hold or dispose of it at will.
Preliminary assessmentThis is closer to consideration for services and may constitute wages and salaries, remuneration for personal services, business income, or other income consistent with the underlying relationship; it cannot be disregarded merely because the funds did not enter a bank card.
What most needs to be proven: who signed the contract, who provided the services, whether the income should belong to the individual or the company, and what the basis for delivery and settlement is.
The greatest risk: where the company undertakes business but an individual collects the payment, or where an individual provides services but the income is recorded as company revenue, the contracting party, the accounting entity, the taxpaying entity and the fund flow will conflict with one another.
II. What Tax Authorities Actually Examine: These Four Matters
Regardless of the number of wallets, first return to asset ownership and the underlying transaction, then answer the following four questions in sequence.
- To whom did the coins originally belong
Were they company treasury assets, the founder's personal assets, customer payments, or funds collected on behalf of a third party? Possession of the private key only demonstrates operational capability and does not by itself prove to whom the asset benefit belongs.
- Why were they transferred
Internal company transfers, custody arrangements, loans, remuneration, profit distribution, expense payments and customer payments do not carry the same tax consequences. "Internal transfer" is merely a note, not a legal conclusion.
- Whether they need to be returned
Can the recipient dispose of the assets at its own discretion, or must it transfer them out in the same amount or as instructed? The return obligation, the period of actual control, and who bears gains and losses on the assets are all important facts for determining asset ownership.
- Whether any new economic benefit has arisen
Has the recipient obtained project payments, consulting fees, wages, handling fees, quantity differentials, or other benefits? If the recipient has obtained disposable economic benefits that it did not previously have, it is necessary to further determine the nature of the income and the time of recognition.
The Implementing Regulations of the Individual Income Tax Law provide that individual income may take the form of cash, physical goods, marketable securities, and other forms of economic benefit. Therefore, the receipt of digital assets does not mean that no income arises merely because the assets did not enter a bank card.
Guoshuihan [2008] No. 818 addresses the situation of purchasing virtual currency from online players and then reselling it to others at a markup and obtaining income, and does not directly regulate transfers between wallets of modern crypto assets. Internal transfers between one's own wallets or company wallets should still be assessed under general principles such as whether income arises and whether asset benefits have been transferred.
Tax authorities look at facts and the chain of evidence, not wallet memos.
III. The boss holding the private keys does not mean the assets belong to the boss personally
This is the issue most easily overlooked by Web3 enterprises.
A company and an individual are distinct legal, accounting, and tax subjects. A founder holding a company wallet's private keys may merely be performing custody and management duties; a transfer of company assets to a founder's personal wallet may also correspond to entrusted holding, a loan, remuneration, profit distribution, or another transaction.
It cannot be assumed that all transfers are from oneself to oneself merely because "the boss manages both wallets."
Enterprises should at a minimum retain:
· A list of company wallets, operating wallets, market-making wallets, and backup wallets;
· Who creates the wallet, who holds the private keys, and who has signing authority;
· The legal and accounting ownership of wallet assets;
· Corporate resolutions, authorizations, and internal approval records;
· The purpose, contracts, and accounting treatment of each transfer;
· Return, handover, and reconciliation arrangements for temporary custody by individuals.
If corporate and personal assets are commingled in a single address over the long term, adding a later statement that "this is the company wallet" will usually have limited probative value. Do not wait until banks, tax authorities, investors, or other shareholders inquire before beginning to explain.
IV. What Is Most Easily Broken in Internal Transfers Is the Cost and Accounting Chain
Transfers among the corporate treasury, operating wallets, and market-making wallets do not necessarily generate new income, but they can easily break the historical cost and accounting records.
For example, the company acquired digital assets through a certain platform in its early days and later transferred them across platforms and wallets multiple times. When disposing of them several years later, only the outgoing transfer record of the last wallet can be seen, and it is impossible to match these assets with the early payments, orders, and accounting records.
The result may not be that "every transfer is taxed," but that at the time of actual disposal it is impossible to accurately explain the source of the assets, the original cost of the property, and the related accounting treatment.
For each wallet transfer, the enterprise should record at least: the outgoing address, incoming address, TxID, time, currency, quantity, reason for the transfer, approver, asset ownership, and the corresponding accounting voucher.
A change of address does not mean income has arisen; but if the evidence and accounting records are broken, this will affect future tax, audit, and bank explanations.
V. Risk has three layers; not every transfer is equally dangerous
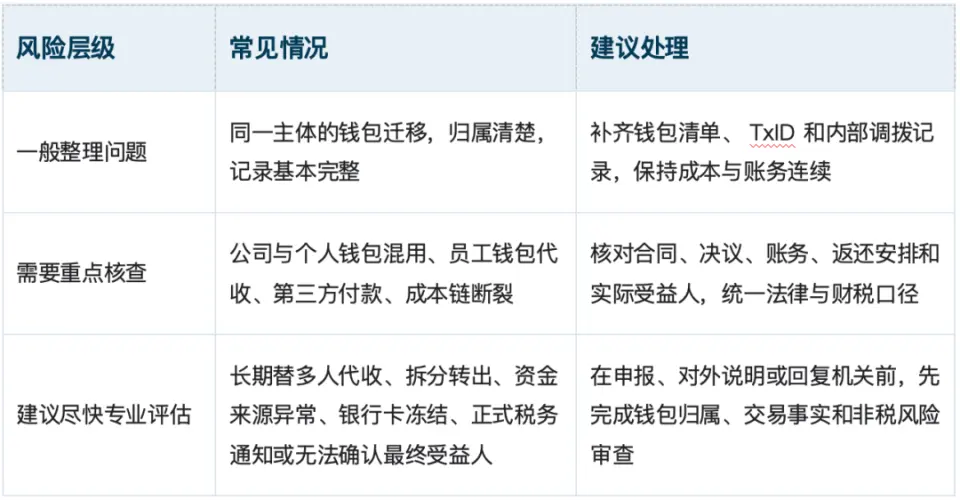
The purpose of risk tiering is not to characterize every token transfer as high risk, but to distinguish which transfers fall within routine governance and which already require moving beyond experience-based explanations.
VI. What business owners can do now
There is no need to wait for inquiries from banks or tax authorities. Enterprises can begin now with four foundational tasks.
Step one: Draw a wallet ownership map
List the company treasury, operational wallets, market-making wallets, founder wallets and wallets temporarily used by employees, and specify: who created each wallet, who holds the private keys, who has signing authority, and to whom the assets actually belong.
Step two: Classify historical transfers
At a minimum, distinguish: transfers within the same entity, company allocations, customer payments, collections by employees or third parties on the company's behalf, loans, compensation or distributions, expense payments and external sales.
Step three: Link on-chain records back to business materials
Match each TxID to the corresponding contracts, invoices or settlement statements, corporate resolutions, accounting vouchers, bank statements and internal approvals. On-chain records show how assets moved; business materials explain why they moved.
Step four: Flag unexplainable transactions in red
Do not hastily enter "internal transfer" or retroactively fabricate materials merely to make the ledger appear complete. List records with unclear ownership, unexplained reasons or mixed use of entities separately, and verify them before filing or submitting any external explanation.
VII. The Three Questions Business Owners Ask Most
- Does a transfer from one company wallet to another company wallet count as income?
If both wallets belong to the same company, and the economic benefit in the assets has not been transferred to another entity and no new consideration has been obtained, the transfer is closer to an internal reallocation of assets. However, it should be supported by records of wallet ownership, approvals, purpose, and accounting.
- If company tokens are held in a wallet controlled personally by the business owner, does that make them the owner's income?
A conclusion cannot be drawn merely from control of the wallet. It is necessary to examine whether the company still enjoys the economic benefit in the assets, whether the owner bears custody and return obligations, and how company resolutions and accounting treat the matter. However, long-term commingling between the company and the individual will significantly increase disputes and the cost of proof.
- If an employee receives tokens on behalf of the company and then transfers them onward, can they simply be labeled as non-income?
Self-labeling alone is not sufficient. It is necessary to prove the genuine entrustment, the return obligation, the correspondence between incoming and outgoing transfers, and that the employee did not obtain any economic benefit. Where there are frequent collections on behalf of the company, split transfers out, or settlement through an employee's bank account, financial regulatory, anti-money laundering, and criminal risks should also be assessed.
Conclusion: First Clarify Wallet Ownership, Then Discuss Whether It Is Income
A wallet is merely a technical carrier. What an enterprise truly needs to answer is: whose assets these are, why they are being transferred, who can dispose of them, whether they need to be returned, and whether a new economic benefit has been created.
If an enterprise has situations such as commingled company and personal wallets, long-term collection on behalf of the company, third-party payments, or historical transactions that cannot be reconstructed, it is advisable to complete verification of wallet ownership and transaction facts before filing tax returns, explaining the source of funds to a bank, or responding to tax authorities.
This article discusses tax compliance, corporate wallet governance, evidence retention, and risk identification. It does not provide channels for crypto asset transactions, trading operations, collection pathways, or investment advice.

