
If someone had said a few years ago that in the future you could buy shares of Apple, Tesla, and Nvidia on the blockchain, most people's first reaction might have been: isn't that just turning stocks into a token? Many people in the crypto industry would even go further and imagine: since they have become tokens, does that mean that in the future, without a broker, without an exchange, and without a clearing institution, holding a wallet would allow you to trade U.S. stocks freely around the world 24/7, just like trading USDT?
Half of this imagination is becoming reality, while the other half may be completely wrong.
In 2026, something highly noteworthy is happening in the U.S. capital markets. On March 18, the U.S. Securities and Exchange Commission (SEC) formally approved Nasdaq's amendment to its trading rules, permitting eligible securities to be traded on Nasdaq in tokenized form.
Then, on September 17, the SEC further introduced an "innovation exemption," allowing eligible tokenized securities trading venues, under certain conditions, to use blockchain, automated market makers, and liquidity pools to trade tokenized U.S. stocks.
Viewed together, the significance of these two developments goes far beyond "the United States permitting tokenized stocks." What the United States is now genuinely beginning to attempt is a larger proposition: whether Wall Street can be moved onto the blockchain.
Of course, "moving" here does not mean shutting down the New York Stock Exchange, eliminating the SEC, or allowing everyone to anonymously open a wallet and speculate in U.S. stocks in the future. On the contrary, what the United States is attempting may be more complex and more realistic: retaining the securities laws, listed companies, shareholder rights, and regulatory system that have operated for more than a century, while gradually migrating some of the underlying technology supporting the operation of that system from traditional databases to the blockchain.
If this experiment ultimately succeeds, what blockchain truly changes may not be "what a stock looks like," but the back office of the entire capital market.
What exactly does putting stocks on-chain mean?
When many people discuss real-world assets (RWA) today—that is, the tokenization of real-world assets—the thing most easily confused is: is the token actually that share of stock?
This question is very important, because on the surface everyone calls them "tokenized stocks," but the legal relationships behind them can be completely different.
On January 28, 2026, the SEC's Division of Corporation Finance, Division of Investment Management, and Division of Trading and Markets issued a staff statement that broadly divides securities tokenization into two categories: tokenization by the issuer or by an entity on behalf of the issuer, and tokenization by a third party unrelated to the issuer. This is staff interpretation of different structures, not a blanket pass for all stock tokens.
These two things look very similar, but their legal significance is completely different.
Take Apple stock as an example. If an issuer or its agent connects a blockchain to a formal securities holder register, a token transfer can correspond to a transfer of securities rights. But issuer participation does not mean the final registration must necessarily occur on-chain: another approach is to notify the issuer of an on-chain transfer and then update the off-chain shareholder register. To determine what investors actually hold, one must look at how the token connects with the statutory registration records.
The second model is far more complex. A platform could first buy one share of Apple stock and place it with a custodian, then separately issue an Apple stock token to you; it could go further still, with the platform not transferring ownership of that one share to you at all, but merely entering into a derivatives contract with you providing that if Apple rises 10%, your token also rises 10%.
On a phone screen, all three things might be called "AAPL," but from a legal perspective they are entirely different types of assets: one may be genuine stock, one may be a securities interest backed by stock, and another may be merely a contract tracking Apple's share price.
This is precisely the most important starting point for understanding today's change. When we see any so-called "stock token" in the future, the first question should not be which chain it is on, but rather: what legal rights actually underlie this token?
The Nasdaq rules approved by the SEC in March center on a tokenization pilot involving the U.S. Depository Trust Company (DTC). Eligible securities may be traded in traditional form or tokenized form; the two forms must be interchangeable, use the same ticker symbol and securities identification code, confer the same rights, and enter the same order book, following the same matching priority. The specific eligible securities, participants and settlement methods remain subject to the pilot conditions.
Suppose you purchase one share of Nvidia stock eligible for the pilot and choose tokenized settlement; this is not purchasing a separate "NVDA coin." The rules seek to preserve the economic identity of the same security and allow investors to choose different forms of holding and recording. Nor does it mean that all on-chain products tracking NVDA are automatically equivalent to this share of stock.
Nasdaq even expressly requires that tokenized securities be fungible with traditional-form securities and confer the same rights and privileges on investors. So if one must use a simple analogy, Nasdaq is not reinventing the stock, but attempting to change the database for stocks.
In the past, stock registration lived in layer upon layer of ledgers maintained by brokers, custodians and clearing systems. Now the United States is beginning to examine: can some of these ledgers be moved onto a blockchain?
This is also why I think simply understanding this matter as "real-world assets (RWA) are hot again" actually underestimates its importance.
How is this different from Binance, Robinhood and Ondo?
From an ordinary user's perspective, it is easy to wonder: Nasdaq, Binance, Robinhood and Ondo are all talking about stock tokenization, so what exactly is the difference between them? The first thing is to distinguish roles: what Nasdaq discusses is trading venues and market rules; for specific products, one must continue to examine who issues, who custodies, who provides the trading access point, and what rights investors ultimately obtain.
The answer is actually still the earlier point: do not look at the token's name; look at the legal structure behind the token.
First, consider the Classic Stock Tokens offered by Robinhood in Europe. According to its official product description, these products are derivative contracts between the user and Robinhood that track the price of a stock or exchange-traded product; they do not directly confer rights in the underlying stock, nor do they therefore confer shareholder voting rights. This refers to this specific product, and products under the same brand in other jurisdictions or with other structures must not be lumped together.
Therefore, purchasing one of these Robinhood stock tokens is not legally the same thing as actually buying one share of Apple stock in a U.S. brokerage account.
Next, consider bStocks, for which Binance provides the trading access point. Its issuer is BTech Holdings Limited, an affiliate of the Binance group. According to official disclosures, each unit of the product is backed 1:1 by underlying securities held by a regulated custodian, but bStocks themselves are not shares of the underlying listed company, nor do they make holders direct shareholders of that company. Whether they can be redeemed for shares and how dividends and corporate actions are handled must still be determined by reference to the issuance documents and platform rules; asset backing and direct shareholding remain two different things.
The U.S. case announced by Ondo and Broadridge in July involves custodied tokenized securities for Micron stock and the BlackRock IVV ETF, as well as governance functions such as shareholder communications and voting. This shows that structures involving third parties may also connect to traditional securities rights, but it cannot be inferred from this that all third-party stock tokens confer the same rights.
Therefore, when comparing these products, one cannot simply look at whether AAPL appears on every screen. Price exposure, rights in custodied securities, and tokenized record forms of the same security differ in the underlying claims, transfer conditions, and risk-bearing arrangements. The brand of the trading access point also cannot replace verification of the issuer and custody arrangements.
For investors, the most practical question is: if the platform or issuer fails, what rights can you assert against whom? Is it a claim for delivery of the underlying securities, for return of assets held in segregated custody, or only a contractual claim to be filed as a creditor? The answer depends on the specific legal documents, asset segregation, and applicable law. For institutions building products and Web3 lawyers, these arrangements must be clearly explained before launch and cannot be left for explanation after a problem arises.
From trading to settlement, how is Wall Street's back office being moved?
When we ordinarily look at the stock market, what we see most easily is the trading interface: how much Apple costs, how much Nvidia costs, click buy, and then the trade is executed. It is therefore easy for us to think that the core of a stock trading system is "matching."
But in reality, after a securities trade is executed, the truly complex matters have only just begun.
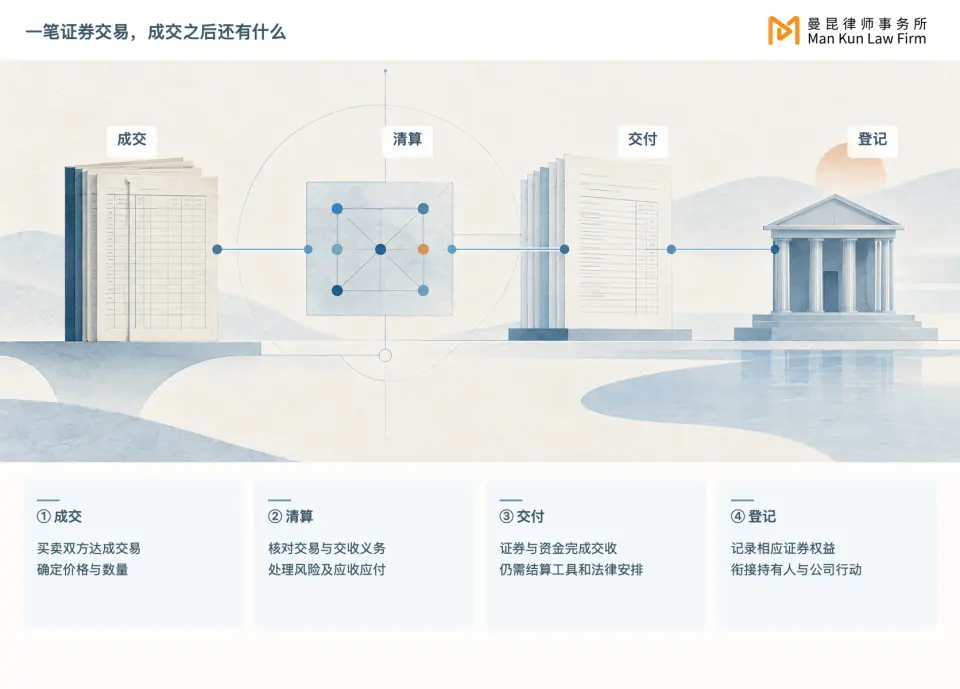
Who is the buyer, and who is the seller? Has the money arrived? Have the shares been delivered? Where is ultimate ownership registered? How do brokers reconcile with one another? How does the central clearing institution handle it? How does the custodian keep records? How are dividends paid? How are voting rights confirmed? And how are stock splits, mergers and acquisitions, and delistings handled afterward?
Together, these things make up the vast post-trade infrastructure of the modern securities market.
Therefore, what the U.S. capital market is truly interested in is not merely "matching a stock trade on-chain," but rather: if the security itself becomes a programmable on-chain asset, can trading, clearing, settlement, registration, and corporate actions begin to converge?
When SEC Commissioner Mark Uyeda discussed securities tokenization this year, the links he mentioned were precisely issuance, trading, transfer, settlement and ownership records. What truly merits attention is whether these actions, previously completed by different institutions, across different databases and at different points in time, may in the future be completed within a single shared ledger or even a single on-chain transaction.
When you click "buy" once on an exchange today, what lies behind it is in fact a long chain of collaboration among financial institutions and databases. In theory, in the future, a single on-chain asset transfer could itself simultaneously serve as the record of the trade, the record of settlement and the record of the change of ownership, and could even further trigger custody arrangements and corporate actions.
Where the corresponding cash settlement instruments, legal effect and risk management arrangements are in place, on-chain systems have the opportunity to link securities delivery and payment more closely. However, trading, clearing, settlement and ownership registration remain distinct stages, and they will not all be completed automatically by a single on-chain transfer.
This may be the efficiency revolution that blockchain can genuinely bring to the capital markets.
Beyond the back office, new options are beginning to emerge even for how the front office executes trades. On September 17, the "innovation exemption" introduced by the SEC opened a temporary, conditional pathway for specified on-chain trading venues.
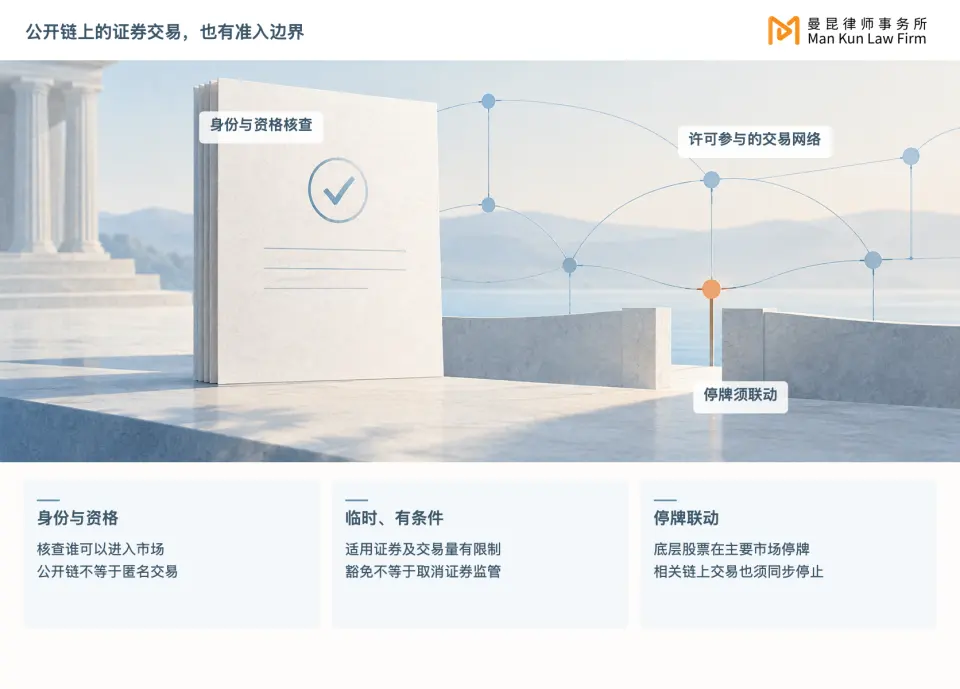
This arrangement permits qualifying tokenized securities trading venues to use permissioned automated market makers and liquidity pools to trade specified tokenized U.S. equities. An automated market maker is a trading mechanism that quotes prices according to programmed rules; a liquidity pool is a centralized pool of assets held for trading. However, the exemption imposes limits on the number of securities and on trading volume, requires verification of holders' rights, and requires that when the underlying stock is suspended from trading on its primary listing exchange, the relevant on-chain trading must also cease accordingly.
What it relaxes is certain regulatory requirements for trading venues once the conditions are met, not the elimination of securities regulation. The relevant exemption is time-limited, and the market is still exploring which rules need to be adjusted.
In the past, we were accustomed to dividing the financial world into two parts: on one side, Nasdaq, the New York Stock Exchange, broker-dealers, central clearing and order books; on the other side, Uniswap, automated market makers, liquidity pools, wallets and blockchain. People have long felt that these two worldviews are entirely different.
But now the SEC has begun to permit a combination that was previously hard to imagine: shares remain securities, but trading mechanisms may begin to draw on decentralized finance.
Shares are still shares, securities law is still securities law, listed companies are still listed companies, and the SEC is still the SEC. But the asset carrier can become a token, ownership registration can use blockchain, automated market makers can appear at trading venues, settlement can gradually move on-chain, investors can manage assets through wallets, and assets may further enter collateral, lending and other on-chain financial protocols.
The regulatory framework has not been overturned, but the technological infrastructure supporting the operation of the regulatory framework is being reshaped by blockchain.
More important than 7×24-hour trading is the "programmability" of assets
Following this logic further, a natural question arises: if stocks are truly put on-chain, can they be traded 24/7 in the future?
Blockchain provides the technical conditions for round-the-clock transfer and trading, but whether the securities market can operate continuously also depends on whether trading rules, market-making liquidity, and the subscription, redemption and risk control of the underlying securities can keep pace. The absence of Saturdays in technology does not mean that financial institutions and the underlying market are ready to operate year-round without interruption.
Some products have already extended trading hours. For example, Binance officially describes bStocks as products that can be traded around the clock. However, the opening of trading in the token market and the opening of trading in the underlying stock market remain two distinct facts.
The ability to buy and sell on weekends does not mean that trades can be executed on weekends at sufficiently good prices. When the underlying market is closed, market makers have fewer options for hedging and replenishing inventory, bid-ask spreads may widen, and on-chain prices may deviate from the most recent transaction price of the underlying securities.
Suppose major news about Nvidia emerges on a Saturday. The relevant token market can reflect investors' judgments in advance, but this price may not equal the price of the underlying stock after trading resumes. For users, what is added is trading opportunities, as well as the possibility of bearing greater price deviation when liquidity is insufficient.
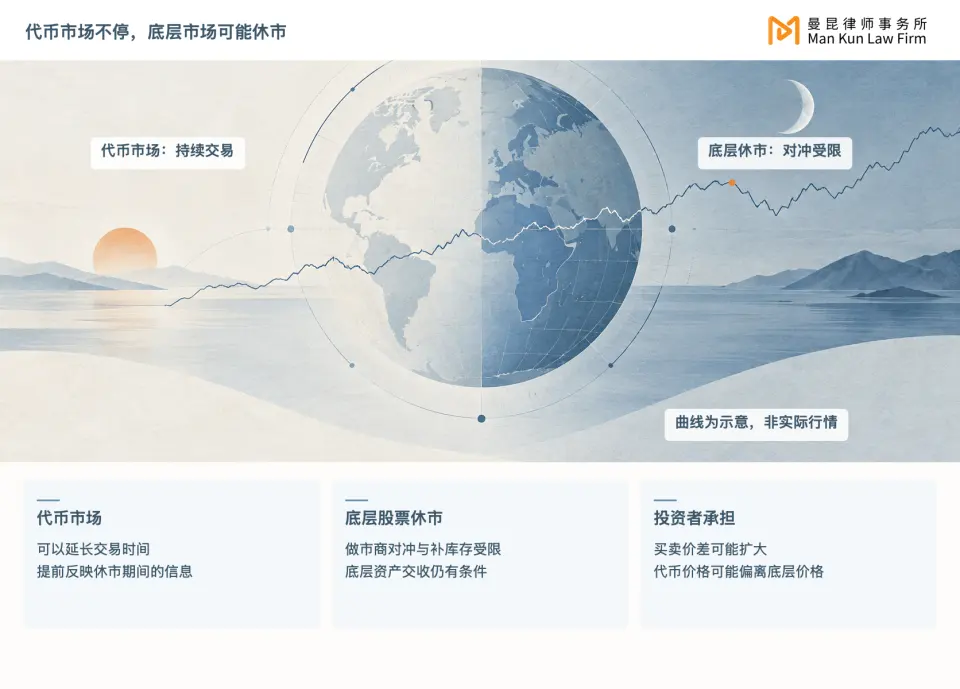
Once this happens, the traditional concepts of "opening price" and "closing price" will begin to lose part of their meaning. Furthermore, the market-making system, option pricing, margin system, risk management, global liquidity distribution, and even the timing of information disclosure by listed companies may all be affected.
Therefore, 24/7 trading does not merely mean "you can also trade stocks at night." Once the capital market becomes a round-the-clock market, many of the institutions on Wall Street built around opening and closing will need to be reconsidered.
If trading hours are merely extended from a few hours a day to 24/7, I believe that is still insufficient to explain the changes that securities on-chain may truly bring. The deeper change is that financial assets begin to have the opportunity to be directly recognized, invoked and combined by programs.
Today you hold 100 shares of Nvidia in a traditional brokerage account. This is of course your asset. But from the perspective of the internet, these 100 shares of Nvidia still exist in a relatively closed financial system. In theory, you can of course pledge the shares, sell them, and participate in various financial services, but each use often requires entering the system of a specific institution. It is difficult for you to directly authorize a program, as you would invoke an internet service, to: pledge 30 of the shares to obtain liquidity, use another 20 shares for other financial strategies, and have an AI agent manage the remaining position according to risk rules you have set in advance.
The problem is not that these financial functions do not exist at all, but that accomplishing these things today requires crossing different institutions and databases. Brokerages have their own books, banks have their own books, fund companies have their own books, and custodians and payment institutions also have their own systems. Assets can of course move among these institutions, but each step of movement may be accompanied by identity verification, authorization, clearing, reconciliation, custody and compliance processes. This is also why traditional finance, although already highly electronic, has not truly achieved "composability" in the internet sense.
If stocks truly become on-chain assets, the situation begins to change. Stocks can become collateral, funds can become collateral, U.S. Treasury bonds can also become collateral, stablecoins can assume settlement functions, and smart contracts can automatically execute financial rules according to pre-set conditions. The different capabilities originally scattered across brokerages, banks, fund companies, payment institutions and on-chain financial protocols then have the opportunity to be built on a more unified asset and settlement network.
This is the "programmability" of assets. It does not mean that all stocks can freely enter any on-chain protocol. Securities on-chain remain subject to restrictions on investor identity, transfer conditions and jurisdictions, and some of these explicit rules can be translated into whitelists, limits and freeze permissions. Code can help enforce rules, but whether the rules are lawful, who has the authority to modify them, and how remedies are provided after errors still require legal and governance arrangements.
If matters truly develop to that point, the change will be more than simply “securities becoming tokens.” In the past, a great many financial rules were written into contracts and enforced by banks, broker-dealers, custodians and back-office personnel; in the future, some of those rules may become financial infrastructure that is automatically executed by code. What is truly being redesigned is not only the form in which assets are represented, but also the manner in which financial rules are enforced.
Putting stocks on-chain does not mean everyone can trade U.S. stocks anonymously
This is the misconception most easily generated when discussing securities tokenization, and it is also something I think is particularly worth explaining clearly today.
Many Web3 users naturally think: since stocks have become tokens on a blockchain, can I simply open a crypto wallet, connect to a decentralized exchange, and buy Apple? Going further, can a Chinese person, an American, an Iranian or a Russian, so long as they hold a wallet address, all trade freely?
At least judging from the regulatory framework currently taking shape in the United States, that is clearly not the case.
The SEC’s “innovation exemption” itself emphasizes a licensed environment. Before allowing users to trade stock tokens, Robinhood likewise requires users to provide identity information and complete the corresponding investor suitability assessment and risk testing.
The reason is not complicated: “securities becoming tokens” and “securities laws disappearing” are two entirely different matters.
This is a sentence very much worth remembering throughout the era of securities tokenization: code can change the form of an asset, but it will not automatically change the legal attributes of that asset.
SEC Commissioner Hester Peirce has in fact already put it very plainly: tokenized securities are still securities.
As a result, many of the original requirements still exist, including customer identity verification, anti-money laundering, sanctions list screening, investor suitability, securities offering rules, market manipulation supervision, insider trading supervision, tax reporting and jurisdictional restrictions, among others.
So what may truly emerge in the future is not necessarily the kind of fully permissionless decentralized finance familiar to everyone today. What is more likely to emerge is a permissioned form of decentralized finance: it looks very Web3, uses a blockchain at the underlying level, holds assets in wallets, completes transactions through smart contracts and may even use automated market makers, but wallets must complete identity verification, the smart contracts themselves may have built-in whitelists, wallets in certain countries and regions may be unable to receive specific securities, and transfers between unverified wallets may also fail to complete.
This may be what the true American version of “on-chain Wall Street” looks like.
Why is this matter more important than real-world assets (RWA) themselves?
Over the past few years, when discussing real-world assets (RWA), the phrase everyone has most liked to use is "moving real-world assets onto the chain." U.S. Treasury bonds on-chain, funds on-chain, real estate on-chain, stocks on-chain—these all sound like the same story. But I increasingly feel that if all we do is package a real-world asset into a token and then take it to a crypto exchange for trading, we have not actually transformed traditional finance.
The underlying stocks may still be purchased by traditional brokers, the assets may still be held by traditional custodians, and the shareholder register may still operate within the traditional securities system; the only difference is that an outermost layer has been added—a token that can circulate on a blockchain. In this sense, it is more a matter of adding a shell of crypto assets around traditional financial assets.
This is certainly not to say that such RWA has no value. On the contrary, it can give traditional financial assets longer trading hours and broader global distribution capabilities, and can also bring these assets into on-chain collateral, lending and trading scenarios that were previously unreachable. But if the core ledger, clearing system, custody system and shareholder registration system of the entire securities market remain unchanged, then strictly speaking, it is more a matter of connecting traditional financial products to the blockchain rather than using the blockchain to transform traditional finance anew.
Therefore, I believe that what is truly noteworthy about Nasdaq's series of moves this year is not that it has added yet another asset class to the RWA market, but that the traditional financial market itself has begun to consider accepting blockchain-based financial infrastructure. This year Nasdaq did not merely amend its own trading rules; it also announced the design of an issuer-centric stock tokenization framework, hoping to incorporate functions such as proxy voting, corporate actions and shareholder communications into the tokenization system. In September, Nasdaq further announced a proposed US$100 million investment in Payward, the parent company of Kraken, and expressly stated that the two sides will continue to cooperate in advancing tokenized stocks, round-the-clock markets, and the connection between the traditional financial system and decentralized networks.
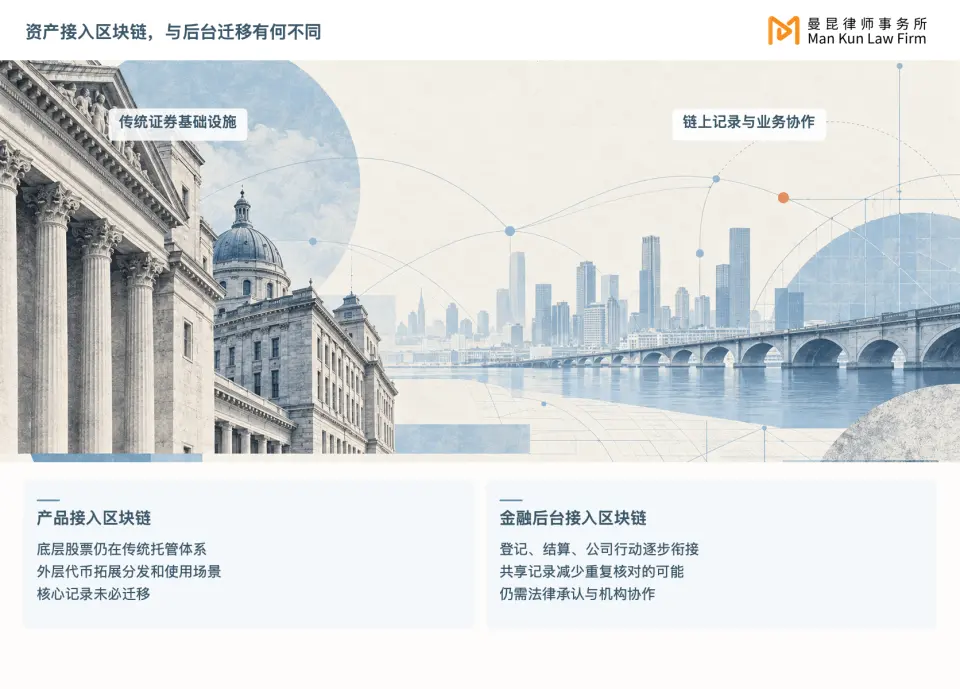
If these moves are viewed together, the question has gradually shifted from "whether Wall Street should study blockchain" to a more fundamental question: on what kind of technological architecture should the next generation of the securities market operate? If traditional securities themselves begin to natively support tokenization, and if central securities depositories, clearing and settlement, shareholder registration and corporate actions all gradually connect with the blockchain, then the boundary between crypto finance and traditional finance—once so clear—will become increasingly blurred.
When we spoke of RWA in the past, the subtext was actually that there exist two different financial systems in the world: one is the "real world," where stocks, bonds, funds and real estate reside; the other is the "blockchain world," where Bitcoin, Ethereum, stablecoins and various on-chain financial protocols reside. So-called RWA is about finding ways to map assets from the first world into the second. But if one day stocks themselves are on-chain assets, funds themselves are on-chain assets, U.S. Treasury bonds themselves are on-chain assets, and the U.S. dollar also circulates on-chain in large volumes through stablecoins, then the very concept of "moving real-world assets onto the chain" may gradually lose its meaning. Because at that time, on-chain and off-chain will no longer be two parallel financial worlds; the blockchain itself will have become part of the real financial world.
From this perspective, what is called RWA today may be merely a transitional concept in the process of migrating financial infrastructure.
Stocks, stablecoins and AI enter the same financial system
Pushing further along this direction, I think a combination very much worth observing will emerge: securities assets such as stocks, stablecoins and AI agents may, for the first time, truly operate on the same set of financial infrastructure. Today these three things are in fact still relatively fragmented: stocks mainly exist within the broker and securities market system, stablecoins mainly operate within the blockchain and crypto finance system, and AI is still mostly helping investors research companies, analyze data and generate investment advice.
But if securities themselves gradually move on-chain, the relationship among the three will change. Suppose that in the future your wallet simultaneously holds Nvidia stock, a U.S. Treasury bond fund and USDC, and an AI agent has been granted a portion of your operating authority; then in theory it could manage these assets according to pre-set rules. For example, when the cash ratio falls below a certain level, it automatically adjusts the money market fund position; when the stock position exceeds the risk threshold, it reduces exposure; when you need short-term liquidity, it obtains stablecoins by pledging U.S. Treasury bonds or eligible securities as collateral, rather than first selling the assets, then transferring U.S. dollars from the broker to the bank, and then entering another financial platform.
In the past, completing such a set of operations required the collaboration of multiple financial institutions, multiple accounts and multiple sets of databases. In the future, if the assets themselves already exist on-chain, part of the process may become collaboration among a wallet, a set of smart contracts and an AI agent. At that point, the role of AI will also change: when we speak of AI investing today, most of the time it is still "AI helps you analyze stocks"; what may truly matter in the future is not AI telling you what to buy, but AI, after obtaining limited authorization, being able to directly manage on-chain financial assets according to explicit rules.
In this scenario, AI can assist in making judgments and issuing instructions, smart contracts are responsible for executing according to conditions, the blockchain records asset status and transfers, and stablecoins provide a settlement tool. The premise for their collaboration is that asset rights are recognized, transaction paths are permitted, and every step remains within the scope of user authorization.
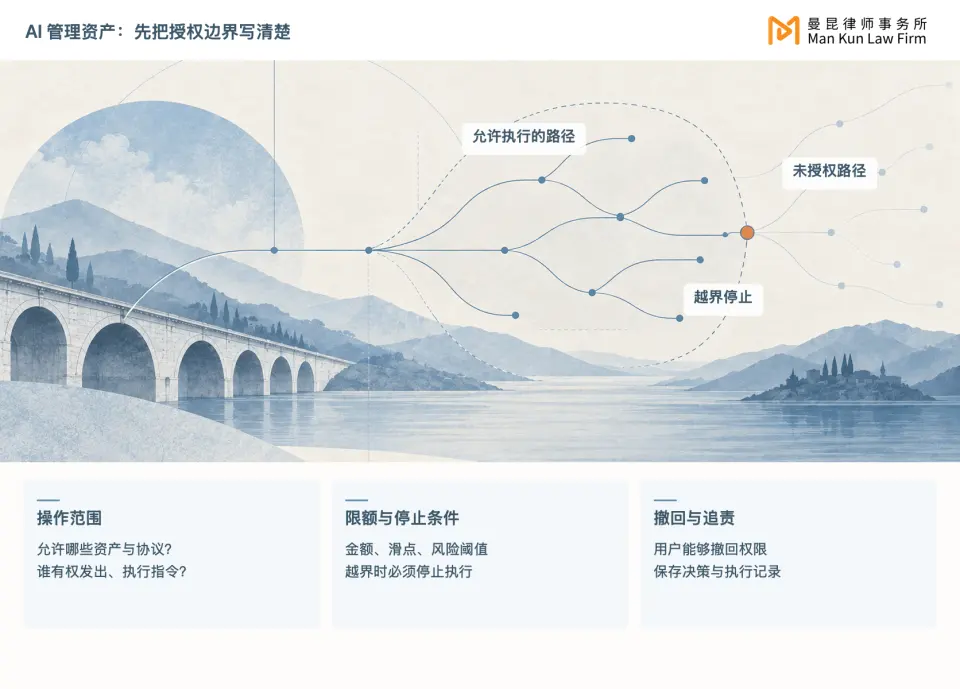
What is most worth designing in advance here is not how much freedom to grant AI, but making the authorization sufficiently specific: the maximum amount it may operate, which protocols it may call, the maximum slippage allowed, the circumstances under which it must stop, and how users may revoke permissions. A general "agree to AI managing assets" is insufficient to answer these questions.
If AI misidentifies risk, a contract executes beyond authorization, or a custody interface malfunctions, to whom will users turn for accountability? Model service providers, wallet operators, strategy providers and custodians need to clarify their respective obligations within the product structure and retain records sufficient to reconstruct the decision-making and execution process. Connecting assets onto the same chain does not automatically connect liability clearly as well.
Commercial competition will change accordingly. Whoever controls the user's wallet entry point, whoever determines which services assets can call, and whoever provides custody, liquidity and compliance execution may capture the corresponding service revenue. Incumbent institutions may not necessarily exit, but they need to re-prove what irreplaceable value they actually provide on this shorter, more automated business chain.
It is not the crypto world swallowing Wall Street, but the two financial worlds beginning to converge
Around securities tokenization, two judgments are common in the market: one holds that it is merely a change of database, the other that exchanges, brokerages and custodians will all be replaced. What concerns me more is, after each infrastructure migration, which services genuinely reduce costs, which institutions still bear necessary responsibilities, and which fees are merely habits left over from history.
Changes in financial infrastructure are rarely completed by completely tearing down the old system. The shift from paper shares to electronic form did not make the stock system disappear; the replacement of trading floors by electronic order books did not make securities regulation disappear; after the spread of internet brokerages, securities exchanges remain the core infrastructure of the capital market. But every migration of underlying technology redefines the value and boundaries of different roles along the industry chain, and blockchain is very likely the same.
This change is the same. Wallets may become the new customer entry point, custodians need to resolve the linkage between on-chain asset control and legal rights, and trading venues need to provide reliable prices and liquidity. The names of institutions may not change, but their competitive positions may already have shifted.
Reality is presenting a hybrid structure: traditional financial institutions absorb the technological capabilities of blockchain, while on-chain finance connects to identity verification, securities rights and investor protection rules. Asset records and operations can be more automated, but dispute resolution, assumption of liability and institutional trust still require someone to be responsible.
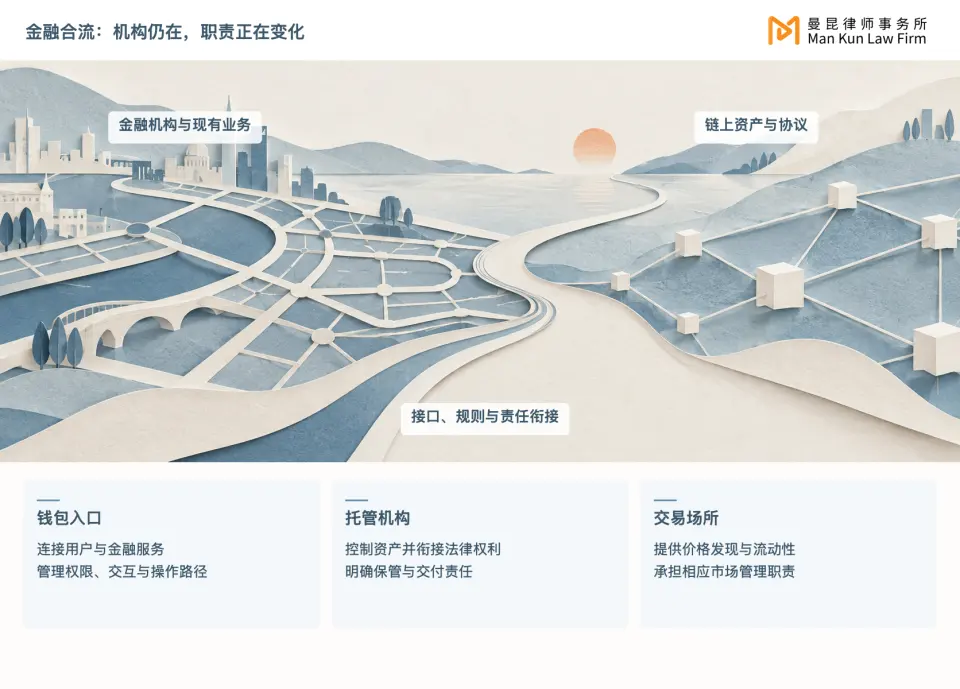
Therefore, to judge how far "Wall Street on-chain" has progressed, one cannot simply count how many tokens have been issued. What is more worth examining is: whether the rights investors acquire are clear, whether assets can be reliably delivered and redeemed, whether trading and settlement are more efficient, and whether there is a clear path for accountability and remedies after the system fails.
When these questions begin to be practically resolved, "moving Wall Street onto the blockchain" will turn from a market story into infrastructure that investors and financial institutions can use. Today's trading rule pilots, tokenized products and on-chain settlement are precisely the concrete entry points for observing this change.
This migration has only just begun.

