July 1, 2026 is not merely an ordinary date on the calendar for projects that continue to operate a crypto-asset business in Europe.
After that date, the longest transitional period that MiCA established for pre-existing crypto-asset service providers comes to an end across the European Union. Service providers that previously conducted business under the former laws of a Member State but have not yet obtained MiCA authorisation should implement orderly wind-down arrangements, cease continuing to provide unauthorised crypto-asset services to EU clients, and properly handle existing client relationships and asset transfers. The previous model of relying on a VASP registration in one Member State and then extending business to other European markets has thereby also reached its institutional end point.
This is precisely why the EU CASP licence has become increasingly important after 2026. It is no longer merely a "high-tier licence" that only large exchanges, custodians or mature platforms need to consider, but is gradually becoming a formal market-access status that must be assessed as a priority when providing services such as wallets, exchange, custody, trade execution, transfers and asset management to EU clients.
What MiCA truly changes is not merely the name of the licence, but the entry of the European crypto business from "separate registration in each country" into a new stage of "unified authorisation, unified standards and cross-border operation".
The EU CASP is not another national-level VASP registration
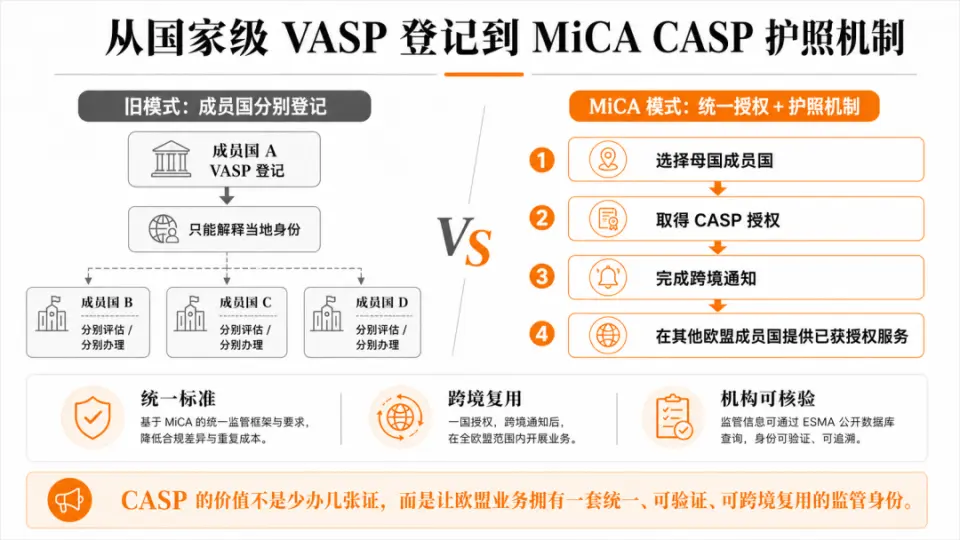
Before MiCA was fully implemented, the regulation of virtual assets in Europe displayed pronounced fragmentation. An enterprise might complete local registration in Lithuania, Poland, France, Italy or another Member State, but different countries had inconsistent requirements regarding scope of business, capital requirements, management personnel and ongoing compliance, and registration in one country generally could not directly prove that the enterprise was entitled to conduct business continuously throughout the entire European Union.
MiCA changed this logic.
Under the MiCA framework, an enterprise in principle needs to apply to the competent authority in the Member State where its registered office is located to become a Crypto-Asset Service Provider, i.e. a CASP. After obtaining authorisation, the enterprise may, through the statutory cross-border notification procedure, provide crypto-asset services already covered by the licence in other EU Member States, without having to reapply in each target market for a complete set of functionally identical licences.
This does not mean that, after a project obtains a CASP authorisation in one Member State, it may conduct all business in Europe without restriction. An enterprise may only provide cross-border services within the scope of its original authorisation, and must still comply with consumer protection, anti-money laundering, marketing and other applicable rules. However, compared with repeated registration in multiple countries in the past, MiCA does indeed provide a clearer set of EU single-market access mechanisms.
For project parties, the greatest commercial value of a CASP is not that there is "yet another European certificate", but that it places clients, business and institutional cooperation across different Member States into a regulatory framework that can be used repeatedly and externally verified.
What business can a single CASP licence actually cover?
MiCA does not grant enterprises a single "crypto licence" in a general manner, but rather divides the scope of crypto-asset services according to actual business functions. The relevant services include holding and administering crypto assets on behalf of clients, operating a crypto-asset trading platform, exchange between crypto assets and funds, exchange between different crypto assets, execution of client orders, placement of crypto assets, reception and transmission of orders, provision of advice on crypto assets, portfolio management, and provision of crypto-asset transfer services on behalf of clients.
Therefore, even for a stablecoin payment product aimed at enterprise clients, its regulatory characterization may be entirely different. If a platform only provides a technical interface that does not control client assets, the scope of CASP application may be relatively limited; however, if the platform receives client stablecoins, controls collection wallets, completes asset conversions, and transfers assets to merchants or suppliers according to client instructions, it may simultaneously involve custody, exchange, and transfer services. If the platform further provides internal trading, order matching, or asset management functions, the scope of authorization required and the intensity of compliance obligations will continue to increase.
A CASP is not a name that a project selects on its own from a service list because it sounds the closest; rather, it is the regulator that determines which permissions the entity should obtain based on the enterprise's product functions, asset control methods, transaction processes, and contractual responsibilities.
MiCA also requires CASPs to maintain corresponding prudential safeguards. The prudential resources an enterprise is required to maintain are generally the higher of the minimum capital requirement corresponding to its business category and 25% of the fixed overhead expenses of the previous year. The broader the scope of the license and the closer the business is to trading platforms, custody, and complex financial services, the higher the capital, governance, technology, and ongoing compliance responsibilities the enterprise is generally required to bear.
A broader license scope is not necessarily more advantageous, because each additional business permission also means the enterprise must demonstrate its ability to bear the corresponding responsibilities on a long-term basis.
Why do banks and institutional clients increasingly value CASP status?
When banks, payment institutions, and institutional clients evaluate crypto projects, the most difficult issues to address are often not whether the enterprise has registration documents, but what registrations in different countries actually mean, whether the license covers the real business, and which entity ultimately bears client assets and regulatory responsibilities.
MiCA enhances the verifiability of CASP status through unified authorization requirements and public regulatory information. The MiCA-related registers and databases established by ESMA can be used to query authorized CASPs and other regulatory information. Partner institutions need not rely solely on license documents presented by the project itself, but can further verify the enterprise's licensing status, home-state regulator, and relevant regulatory records.
More importantly, CASP authorization is not merely a review of a set of written policies. In its supervisory materials on authorization, ESMA emphasizes that regulators need to focus on reviewing the enterprise's actual operations, corporate governance, business plan, outsourcing arrangements, information technology, and anti-money laundering systems; for applicants with large-scale cross-border activities, complex group structures, or heavy reliance on overseas outsourcing, more in-depth review should be conducted.
This means that an enterprise able to obtain and continuously maintain CASP authorization needs to demonstrate to the regulator that: the project has a genuine EU entity and management arrangements, the business plan is consistent with the actual product, client assets and company assets can be distinguished, key technology and compliance functions have not been left entirely outside the EU, and there are enforceable handling mechanisms in the event of system failures, client complaints, or market exit.
A CASP cannot guarantee that a bank will definitely open an account, nor can it guarantee that a major client will definitely sign a contract, but it can provide banks and institutions with a unified regulatory language for due diligence.
It is difficult for non-EU projects to continue relying on "offshore entities plus passive client acquisition"
For some Asian or offshore crypto projects, the common path in the past was to retain an offshore operating entity and argue that European clients actively found the platform, so the enterprise did not need to obtain a local license in the EU.
MiCA does indeed retain a very limited reverse solicitation exception, namely reverse solicitation, but ESMA expressly requires that this exception be interpreted strictly and narrowly. Only where a client, entirely on its own initiative, requests to receive a specific service may an overseas entity potentially provide the service within the corresponding scope; if a project reaches EU clients through advertising, search engine optimization, social media, influencer promotion, traffic referral by EU-affiliated companies, or other means, it may be deemed active solicitation and may no longer rely on this exception.
The impact on globalized projects is very direct. If a platform sets up a European-language website, places advertisements targeting the European market, deploys EU sales personnel, or continuously receives traffic referrals from European partners, it cannot merely write a sentence in the user agreement that "the client contacted us on its own initiative" as a substitute for the formal CASP pathway.
In the MiCA era, whether a project enters the EU market depends not only on where the company is registered, but even more on to whom the enterprise is actually marketing, with whom contracts are signed, and which entity truly provides the services.
CASP is important, but it is not a universal card for EU financial business
MiCA primarily covers crypto assets that are not already governed by other EU financial services laws. If a certain type of token constitutes a financial instrument based on its actual rights and economic attributes, the securities regulatory framework such as MiFID II may apply, rather than being automatically classified under MiCA simply because blockchain technology is used.
For crypto payment projects, another issue requiring close attention is the interface between electronic money tokens and payment services regulation. If a platform transfers, on behalf of clients, stablecoins that meet the definition of electronic money tokens, some activities may simultaneously have the nature of payment services; therefore, in addition to MiCA CASP authorization, the project may also need to assess payment institution licensing under PSD2, or cooperate with a licensed payment institution. The EBA has already issued dedicated opinions and transitional arrangements regarding the interface between MiCA and PSD2, indicating that CASP status does not automatically cover all stablecoin payment functions.
Likewise, CASP cannot automatically cover client fiat currency accounts, merchant acquiring, bank cards, electronic money issuance, or traditional cross-border remittances. A payment platform that simultaneously connects stablecoins and fiat currency often needs a CASP entity to undertake crypto asset services, while a PI, EMI, bank, or other payment institution completes the fiat-side functions.
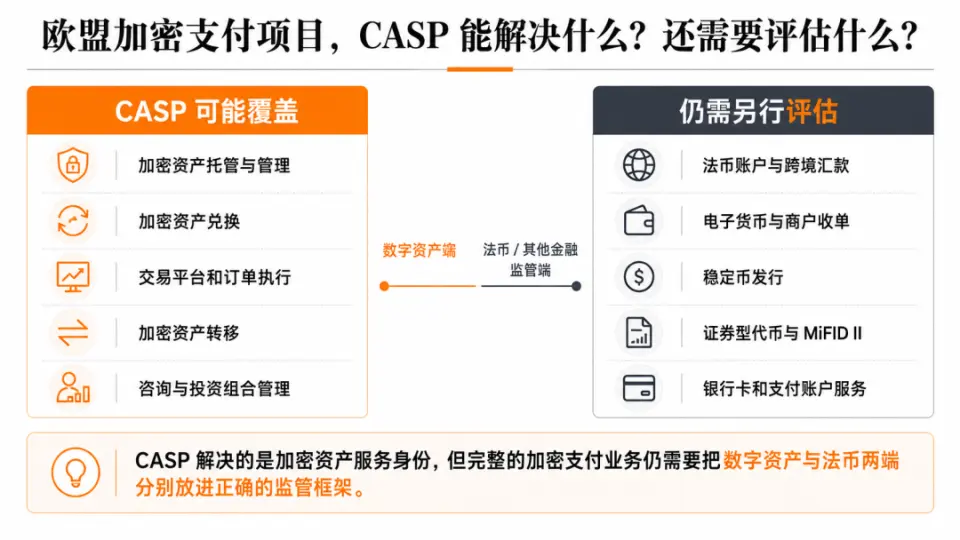
CASP addresses crypto asset service status, but a complete crypto payment business still requires placing the digital asset side and the fiat side separately into the correct regulatory frameworks.
Which projects should prioritize MiCA CASP?
The first category is trading, wallet, custody, exchange, and payment platforms that have clearly designated the EU as their primary market and plan to serve clients in multiple member states over the long term. If such projects continue to rely on overseas entities or old national registrations, they will not only find it difficult to support cross-border marketing and institutional cooperation, but will also directly face market access issues after the maximum transition period ends.
The second category is projects preparing to cooperate with EU banks, EMIs, PIs, large merchants, or institutional clients. Such counterparties will usually require the project to explain the scope of its CASP license, the manner in which client assets are controlled, the home member state competent authority, and cross-border notification circumstances, and will verify the true division of labor between EU entities and overseas entities within the group.
The third category is groups that have already achieved a certain trading scale and wish to concentrate business across multiple European countries into a single regulated entity. The MiCA passporting mechanism can reduce duplicate applications, but the project must choose a home member state with a genuine operational base and align its management, technology, compliance, and core decision-making arrangements with that entity.
Conversely, if a project is still at the product validation stage, has no clear European customer and market plans, and does not yet intend to conduct marketing and continuous services in the EU, directly initiating a CASP application may be excessive. A more reasonable approach is to first define the market boundaries, limit EU business, and design the future entity and product structure in advance in accordance with MiCA requirements.
What can Mankun deliver for a project?
For crypto payment and digital asset projects preparing to enter the EU, Mankun can first, by focusing on product functions, token types, customer regions, wallet control methods and fiat settlement arrangements, produce the MiCA Business Model Compliance Diagnostic Opinion, the CASP Service Scope and Regulatory Identity Matrix, and the MiCA, MiFID II and Payment Services Applicability Analysis, to help the project determine which businesses fall within the CASP scope and which functions may touch upon securities or payment regulation.
After the CASP path is determined, Mankun can compare the competent authorities, substantive operation requirements, team configuration, application pace and banking environment of candidate member states, and produce the EU CASP Jurisdiction Comparison Report, the Home Member State Selection Plan and the EU Market Access Roadmap. The focus of the comparison is not to find the country with the most lenient approval, but to choose the regulatory landing point that best matches the project's customers, team and long-term business.
Mankun can further design the division of labor among the EU CASP entity, the offshore technology company, the group holding entity, banks and payment institutions, and produce the EU Group Entity Structure Chart, the On-Chain and Off-Chain Fund Flow Chart, the Customer Asset Control and Segregation Plan and the Group Function and Regulatory Responsibility Matrix.
After entering the application stage, Mankun can assist in preparing the CASP business plan, corporate governance, prudential safeguard arrangements, AML/KYC/KYT policies, customer asset protection, outsourcing and technology risk documents, complaint handling and exit plans, and simultaneously prepare the due diligence explanatory materials required by banks, EMIs, institutional customers and regulatory authorities.
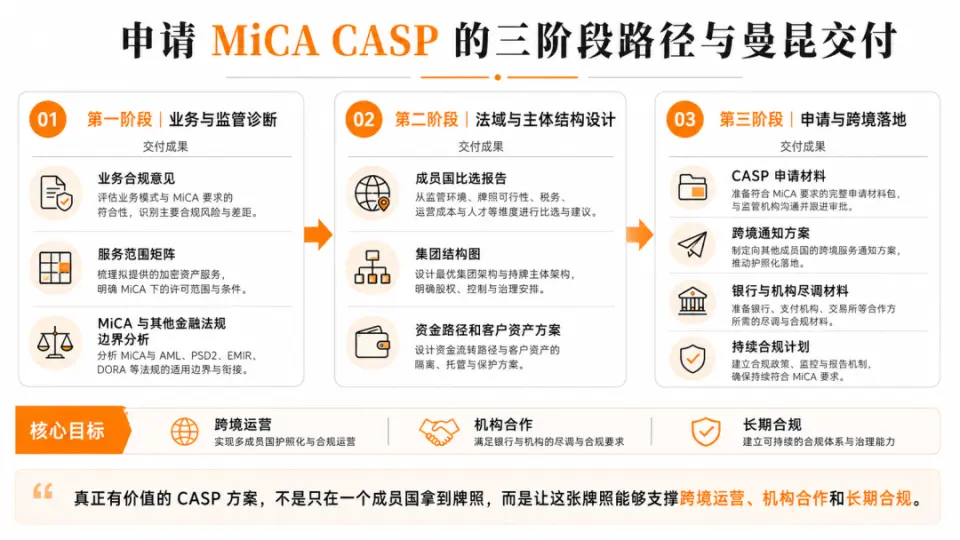
What Mankun delivers is not a set of application documents used only to obtain a license, but an implementation plan that can continue to support cross-border operations, bank cooperation, institutional customer due diligence and ongoing compliance.
The importance of CASP stems from the fact that there is no longer a "fuzzy transition zone" in the European market
When MiCA was just adopted, the market focused more on the fact that Europe finally had a unified set of crypto regulatory rules; by 2026, the truly important change is no longer the rules themselves, but that the longest transition period has ended, unauthorized projects need to exit, and banks and institutional customers have begun to re-screen cooperation partners according to MiCA standards.
For crypto projects hoping to enter Europe, CASP is not a license that can be temporarily placed in promotional materials, but a foundational structure connecting customer access, cross-border operations, bank cooperation and group responsibility.
It cannot solve all fiat payment, stablecoin issuance and securities regulation issues, nor can it replace a real team and ongoing compliance capabilities; but if a project is preparing to provide crypto asset services in the EU for the long term, CASP has gradually shifted from "worth considering" to a regulatory entry point that "must be clearly explained."
In the MiCA era, the EU CASP is becoming increasingly important, not because Europe has added another license, but because Europe finally recognizes only one unified crypto asset service identity that can be subject to unified supervision.
In the next article, we will continue to discuss:Global Crypto Payment Compliance Map · Advanced Series ④ | Lithuania CASP: A High-Efficiency Option Among EU Crypto Licenses
/ END.
*This article is an original work of Mankun Law Firm and represents only the personal views of the author. It does not constitute legal consultation or legal advice on any specific matter. For reprinting and legal consultation, please add our customer service:mankunlawyer。
Author of this article