
On September 16, 2026, Hong Kong published the first five-year plan since its return to China — the First Five-Year Plan for Economic and Social Development of the Hong Kong Special Administrative Region (2026–2030).
The significance of this is, of course, substantial.
Since the return, the city's economic and social development direction has mainly been advanced along two tracks: one is the Chief Executive's annual Policy Address, which covers one year; the other is the dedicated blueprints and industry plans of the various policy bureaux, which cover one sector.
What has consistently been missing is a medium-term development framework that spans government terms, covers the entire city, and is expressly aligned with the five-year plan.
This time, that gap has been filled. And the manner in which it has been filled is highly indicative: the plan states at the outset that it was formulated in the opening year of the national 15th Five-Year Plan, and that its main thread is "integrating into and serving the overall national development agenda."
The supporting implementation mechanisms are also set out in full.
The plan establishes a closed loop: the Policy Address sets the annual work programme, the Budget provides resource support, the Chief Executive reports on implementation when delivering the annual report to the President and the Central Government, and monitoring, evaluation and mid-term adjustments are carried out during the five-year period.
The document lists 105 indicators in total — 22 main indicators, 57 work indicators and 26 main-text indicators.
A document with indicators, resources, assessment and feedback mechanisms is a different matter from a document of stated positions. For businesses operating in Hong Kong and for teams preparing to enter the Hong Kong market, the policy certainty of the next five years will mainly derive from this document.
The full text runs 124 pages, and I have read it.
The first thing I did after finishing was to open the full text and search for keywords. The results were more interesting than I had expected.
First, a set of figures.
I searched the full Chinese version on the official website word by word, and the results are shown in the figure below.
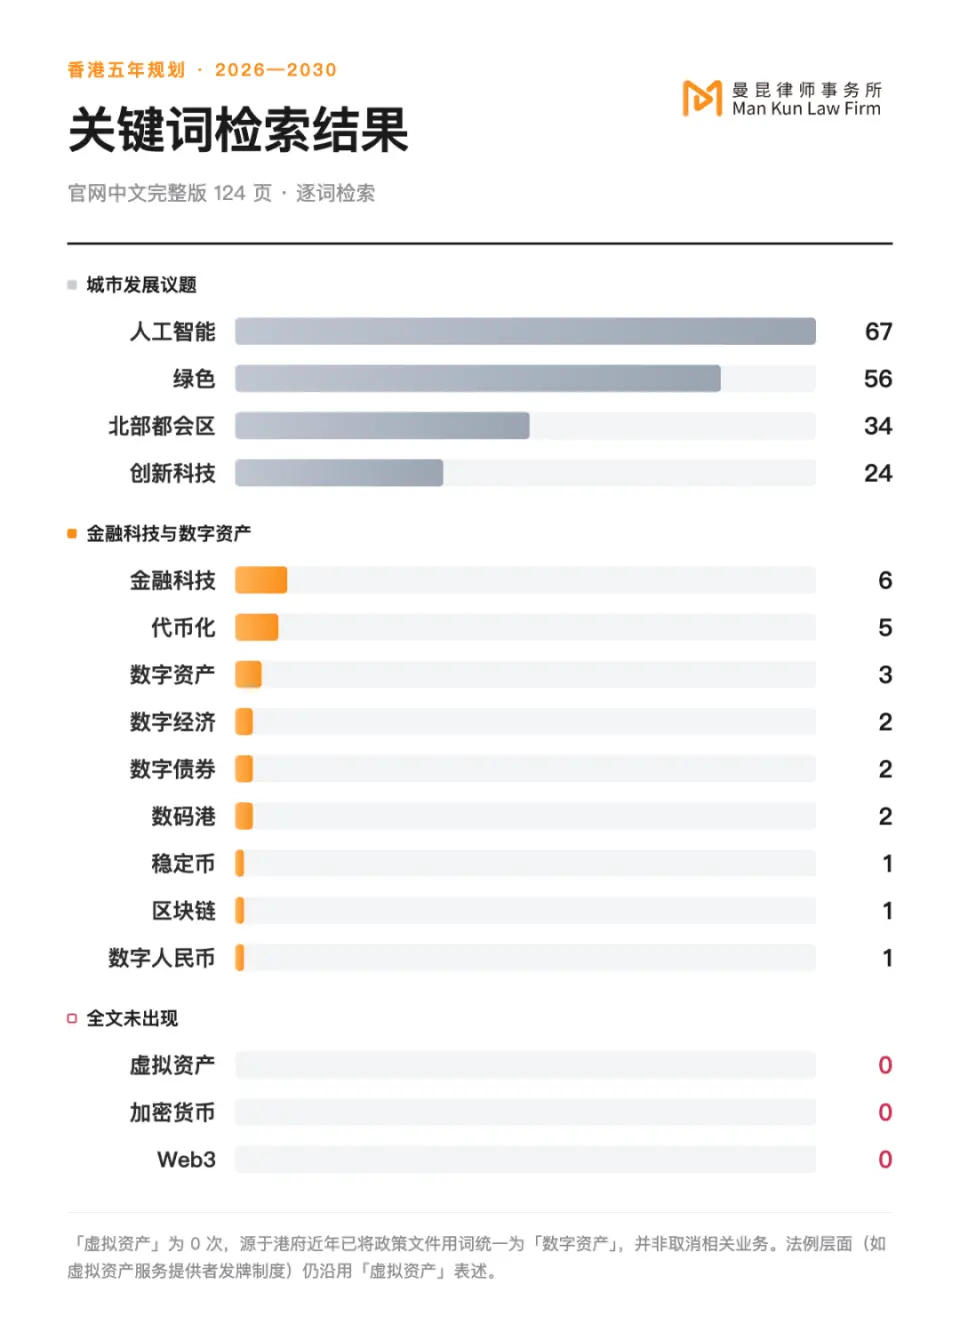
Keyword search results for the Hong Kong Five-Year Plan (2026–2030)
Several comparisons are worth remembering first: artificial intelligence 67 times, green 56 times, Northern Metropolis 34 times, innovation and technology 24 times; fintech 6 times, tokenization 5 times, digital assets 3 times; stablecoins, blockchain and digital renminbi once each.
To avoid any misunderstanding among readers, I should first explain that "virtual assets" appears 0 times in this document not because the Hong Kong government intends to avoid the term, but because the government has already completed the unification of terminology.
In October 2022, the Financial Services and the Treasury Bureau issued the "Policy Statement on the Development of Virtual Assets in Hong Kong," which used "virtual assets" (Virtual Assets). By June 26, 2025, the "Policy Statement 2.0 on the Development of Digital Assets in Hong Kong" issued by the same bureau had already switched to "digital assets" (Digital Assets). Since then, policy-level formulations have largely been unified under the latter, and this Five-Year Plan continues precisely that formulation.
So the 0 occurrences indicate a change of wording, not the cancellation of cryptocurrency-related business.
Which chapter it appears in
The 3 occurrences of "digital assets" are all concentrated in Chapter 6, "International Financial Centre," Section 4 — "Advancing 'Finance+' to Enable Financial Services to Serve the Real Economy."
What is "Finance+"? It means finance plus various scenarios. The Plan lists six directions: technological innovation, trade, green development, intellectual property, shipping, and people's livelihood. Digital assets and tokenization are placed within the single direction of "Finance + Technological Innovation."
It is not a standalone chapter, nor a standalone section. It is one sentence within a long paragraph of a section.
This placement is itself the answer.
If Hong Kong wanted to build crypto into an industry, the normal approach would be to open a separate chapter and set out regulation, licensing, talent, the market and industry scale clearly. This Plan does not do that. It places digital assets in the drawer of "how finance serves the real economy."
Let me copy a few key sentences from that passage:
Adhere to the principle of "same business, same risks, same rules," build a globally leading licensing and regulatory regime for digital assets, and promote digital asset liquidity and market innovation and development.
The four items in "Box 3" that follow are more specific actions:
Steadily advance the development of financial technology, including four key areas: data and payment infrastructure, artificial intelligence, resilience enhancement, and financial tokenisation.
Through the Hong Kong Monetary Authority's Ensemble project, promote the use of tokenisation technology to enhance further practical application across multiple asset classes and use cases.
Prudently promote the development of emerging digital assets such as central bank digital currencies (CBDCs), stablecoins, tokenised deposits, tokenised bonds, and tokenised securities products.
Deepen the application of the financial regulatory sandbox, expand its coverage, and achieve a dynamic balance between financial innovation and regulation.
Four sentences, four actions. Not many words, but each sentence lands on something concrete.
These four actions are all very concrete
I want to break them down one by one.
The first sentence is the principle.
The phrase "same business, same risks, same rules" was not invented by the plan. When the Legislative Council passed the Stablecoins Ordinance in May 2025, the then Secretary for Financial Services and the Treasury, Christopher Hui, used exactly this phrase. The plan copied it verbatim, effectively upgrading a regulatory statement into an institutional principle for the next five years.
For those doing business, this statement cuts both ways: a business does not enjoy looser rules merely because it is wrapped in an "on-chain" shell; conversely, so long as the substance of the business is the same, the regulatory approach is predictable. For teams that do things seriously and do not intend to make money off gray areas, this is in fact good news.
The second sentence concerns scope.
"Financial tokenization" is listed among the four key areas of fintech; the other three are data and payment infrastructure, artificial intelligence, and enhanced resilience. Of the four, tokenization is the only one that points directly at "how assets go on-chain."
This ordering is also informative. Data and payment infrastructure ranks first, indicating that Hong Kong understands the foundation of digital finance as "data and payments," rather than "coins."
The third sentence concerns the implementation lever.
The plan names the HKMA's Ensemble project. The HKMA launched this project in March 2024 and, in August of the same year, launched the Ensemble Sandbox, which focuses on completing settlement between banks using experimental tokenized money: participating banks connect their respective tokenized deposit platforms to the sandbox to test real transaction processes such as interbank payment versus payment (PvP) and delivery versus payment (DvP).
The first batch of experiments covers four themes: fixed income and investment funds, liquidity management, green and sustainable finance, and trade and supply chain finance.
I am not particularly fond of the word "ecosystem," but this is indeed about building an ecosystem. What it tests is not "issuing a coin," but how things such as bonds, funds, and green assets can complete issuance, trading, and settlement through tokenization.
The fourth sentence concerns the list.
"Central bank digital currency (CBDC), stablecoins, tokenized deposits, tokenized bonds, and tokenized securities"—five categories, identified very clearly. Two characters are also added in front: "steady and prudent."
These two characters are important. This document does not say "vigorously develop"; it says "steadily and prudently promote." The direction is given; the pace is controlled.
The final sentence concerns the boundary. The regulatory sandbox is to be expanded. The logic of a sandbox is to allow you to trial and error in a controlled environment, but with someone watching. This is both an opening for innovation and a boundary that has been drawn.
After reading it, my assessment is this: on the matter of digital assets, what Hong Kong offers is certainty, not imagination.
The licensing pathway will become clearer, and compliance standards will become more explicit; but the path of "issuing tokens and telling stories" will receive no support whatsoever in Hong Kong.
The supporting clues are hidden elsewhere
If one looks further back, one finds several other clues in the plan that echo digital assets.
One is financial risk prevention. After the section on "finance+", the very next section is entitled "Strengthening Financial Risk Prevention", which includes a separate sentence: consolidating cybersecurity, fintech supervision and anti-money laundering capabilities.
Anti-money laundering and cybersecurity are singled out by name, which shows that the regulators understand where the risk points in this type of business lie. For practitioners, this means compliance costs will not fall and licensing thresholds will not be relaxed.
One is digital bonds. The plan states that it will "steadily advance the regular issuance of government digital bonds, improve the relevant legal and market supporting arrangements, and promote the popularization of digital bonds", while also advancing the commercialization, internationalization and modernization of the Central Moneymarkets Unit (CMU).
Hong Kong has already issued several rounds of government digital bonds; "regular issuance" means they are no longer a pilot but a routine instrument. The accompanying modernization of the CMU is an upgrade of the infrastructure at the custody and settlement layer.
One is Cyberport. The plan positions Cyberport as a southern cluster focused on digital technology, with the direction spelled out in parentheses: "artificial intelligence, cybersecurity, blockchain and fintech". In the entire text, "blockchain" appears only this once, right here.
One is digital trade. This part discusses expanding the import and export of digital technologies, digital products and digital services, and includes in parentheses a reference to "Token". Here "Token" is closer to the term as used in the artificial intelligence context, but its appearance in the digital trade chapter also shows that the boundary of "digital products" is widening.
There is also one in Qianhai. The plan mentions supporting Shenzhen and Hong Kong in jointly adopting cross-border RMB settlement and the digital RMB. The digital RMB appears in this section, placed together with RMB internationalization.
Stringing these clues together, the main thread is actually quite clear.
My three judgments
First judgment: the real main thread is the digital foundation for RMB internationalization, and crypto is a supporting player.
Viewed together—the offshore RMB hub, the application of the digital renminbi in Qianhai, government digital bonds, CMU modernization, CBDC, tokenized deposits and tokenized bonds—these point in the same direction: making the renminbi more usable in cross-border trade, investment and settlement, and carrying it through digital means.
Digital assets are a technical module on this foundation, not the foundation itself. What recurs throughout the plan is "RMB-denominated" "RMB settlement" "cross-border RMB", rather than "cryptocurrency"
This also explains why the plan adopts the expression "digital assets". Its scope is broad enough to accommodate the digital forms of traditional finance such as CBDC, digital bonds and tokenized deposits; "virtual assets" has a narrower reach and has long been tied to the crypto-circle context, and is insufficient to carry an agenda this broad.
Second judgment: the division of roles between Hong Kong and the mainland in this field is clearer than many people think.
The mainland's rules do not touch token financing or trading speculation; what Hong Kong does is, under the common law system, bring digital assets into the licensing and regulatory framework, becoming the interface at the institutional boundary.
This plan does not overstep. It does not say anything is to be liberalized; it only says institutions are to be built, tokenization carried out, and sandboxes piloted. All actions stay within the framework of "financial infrastructure".
For practitioners, the practical meaning of this boundary is: for business facing the mainland, do not expect the rules to loosen; for licensed business facing Hong Kong and international markets, certainty is increasing.
Third judgment: in the next five years, digital assets will not become Hong Kong's "main battlefield", but will become a "must-have"
Just look at the indicators.
Among the 105 indicators listed in the plan, 22 main indicators include hard targets such as 900 hectares of developed land in the Northern Metropolis, 70,000 residential units, 196,000 public housing units, and innovation activity expenditure as a share of GDP striving to reach 3% after 2030.
There is not a single indicator concerning digital assets.
This is not a lack of attention, but a question of positioning. The Northern Metropolis is an engineering project that requires land, money and time, so it must have hard indicators. Digital assets involve institution-building, and progress depends on the market and the international environment, so they are not suited to hard indicators.
A more accurate assessment, therefore, is this: it is not the main focus, but it is a standard component. By 2030, an international financial center that still lacks mature tokenization infrastructure and a digital asset regulatory regime would not be viable.
How practitioners can make good use of this document
I am accustomed to treating policy documents as a yardstick for judgment rather than as directives for action. This plan can be used in the following ways.
Look at direction: the following categories are encouraged:
First, tokenization itself. Bonds, deposits, securities, funds and green assets are expressly mentioned in the plan, and the HKMA sandbox is already running.
Second, payment and settlement infrastructure. Data and payment infrastructure is listed as the first key area of fintech.
Third, compliance and risk management tools. Fintech regulation, anti-money laundering and cybersecurity are singled out, which means demand in these areas is certain.
Fourth, innovation within the sandbox. The regulatory sandbox is to be expanded, and for projects that can enter the sandbox, this is a relatively safe channel for trial and error.
Look at boundaries: the following are not readily supported:
The token-issuance narrative. The term "digital assets" in the policy document points to licensed operations, tokenization and infrastructure, not token issuance.
Trading and speculation. The plan provides no policy support for trading-related business; the accompanying chapters emphasize risk prevention.
Retail-oriented financial innovation for the mainland. This point requires no elaboration.
Finally, here is a pragmatic method of assessment.
Break your business down into three layers: the technology layer, the service layer, and the financialization layer. For the technology and compliance services layers, the direction is sound; for the financial services layer, first check whether you hold a license and whether a sandbox is available. If you do, you can proceed; those seeking to raise funds and pocket money by issuing tokens at the edges of regulation may as well call it a day.
Alright, meeting adjourned.

